Markets Today - October 14, 2026
Oct 14•4 min read
.png)
Daily analysis of crypto markets and the forces shaping them, from the Nexo research desk.
Bitcoin slides to $82,000 as hot CPI puts a December Fed hike near 95%, with October odds up to 43%
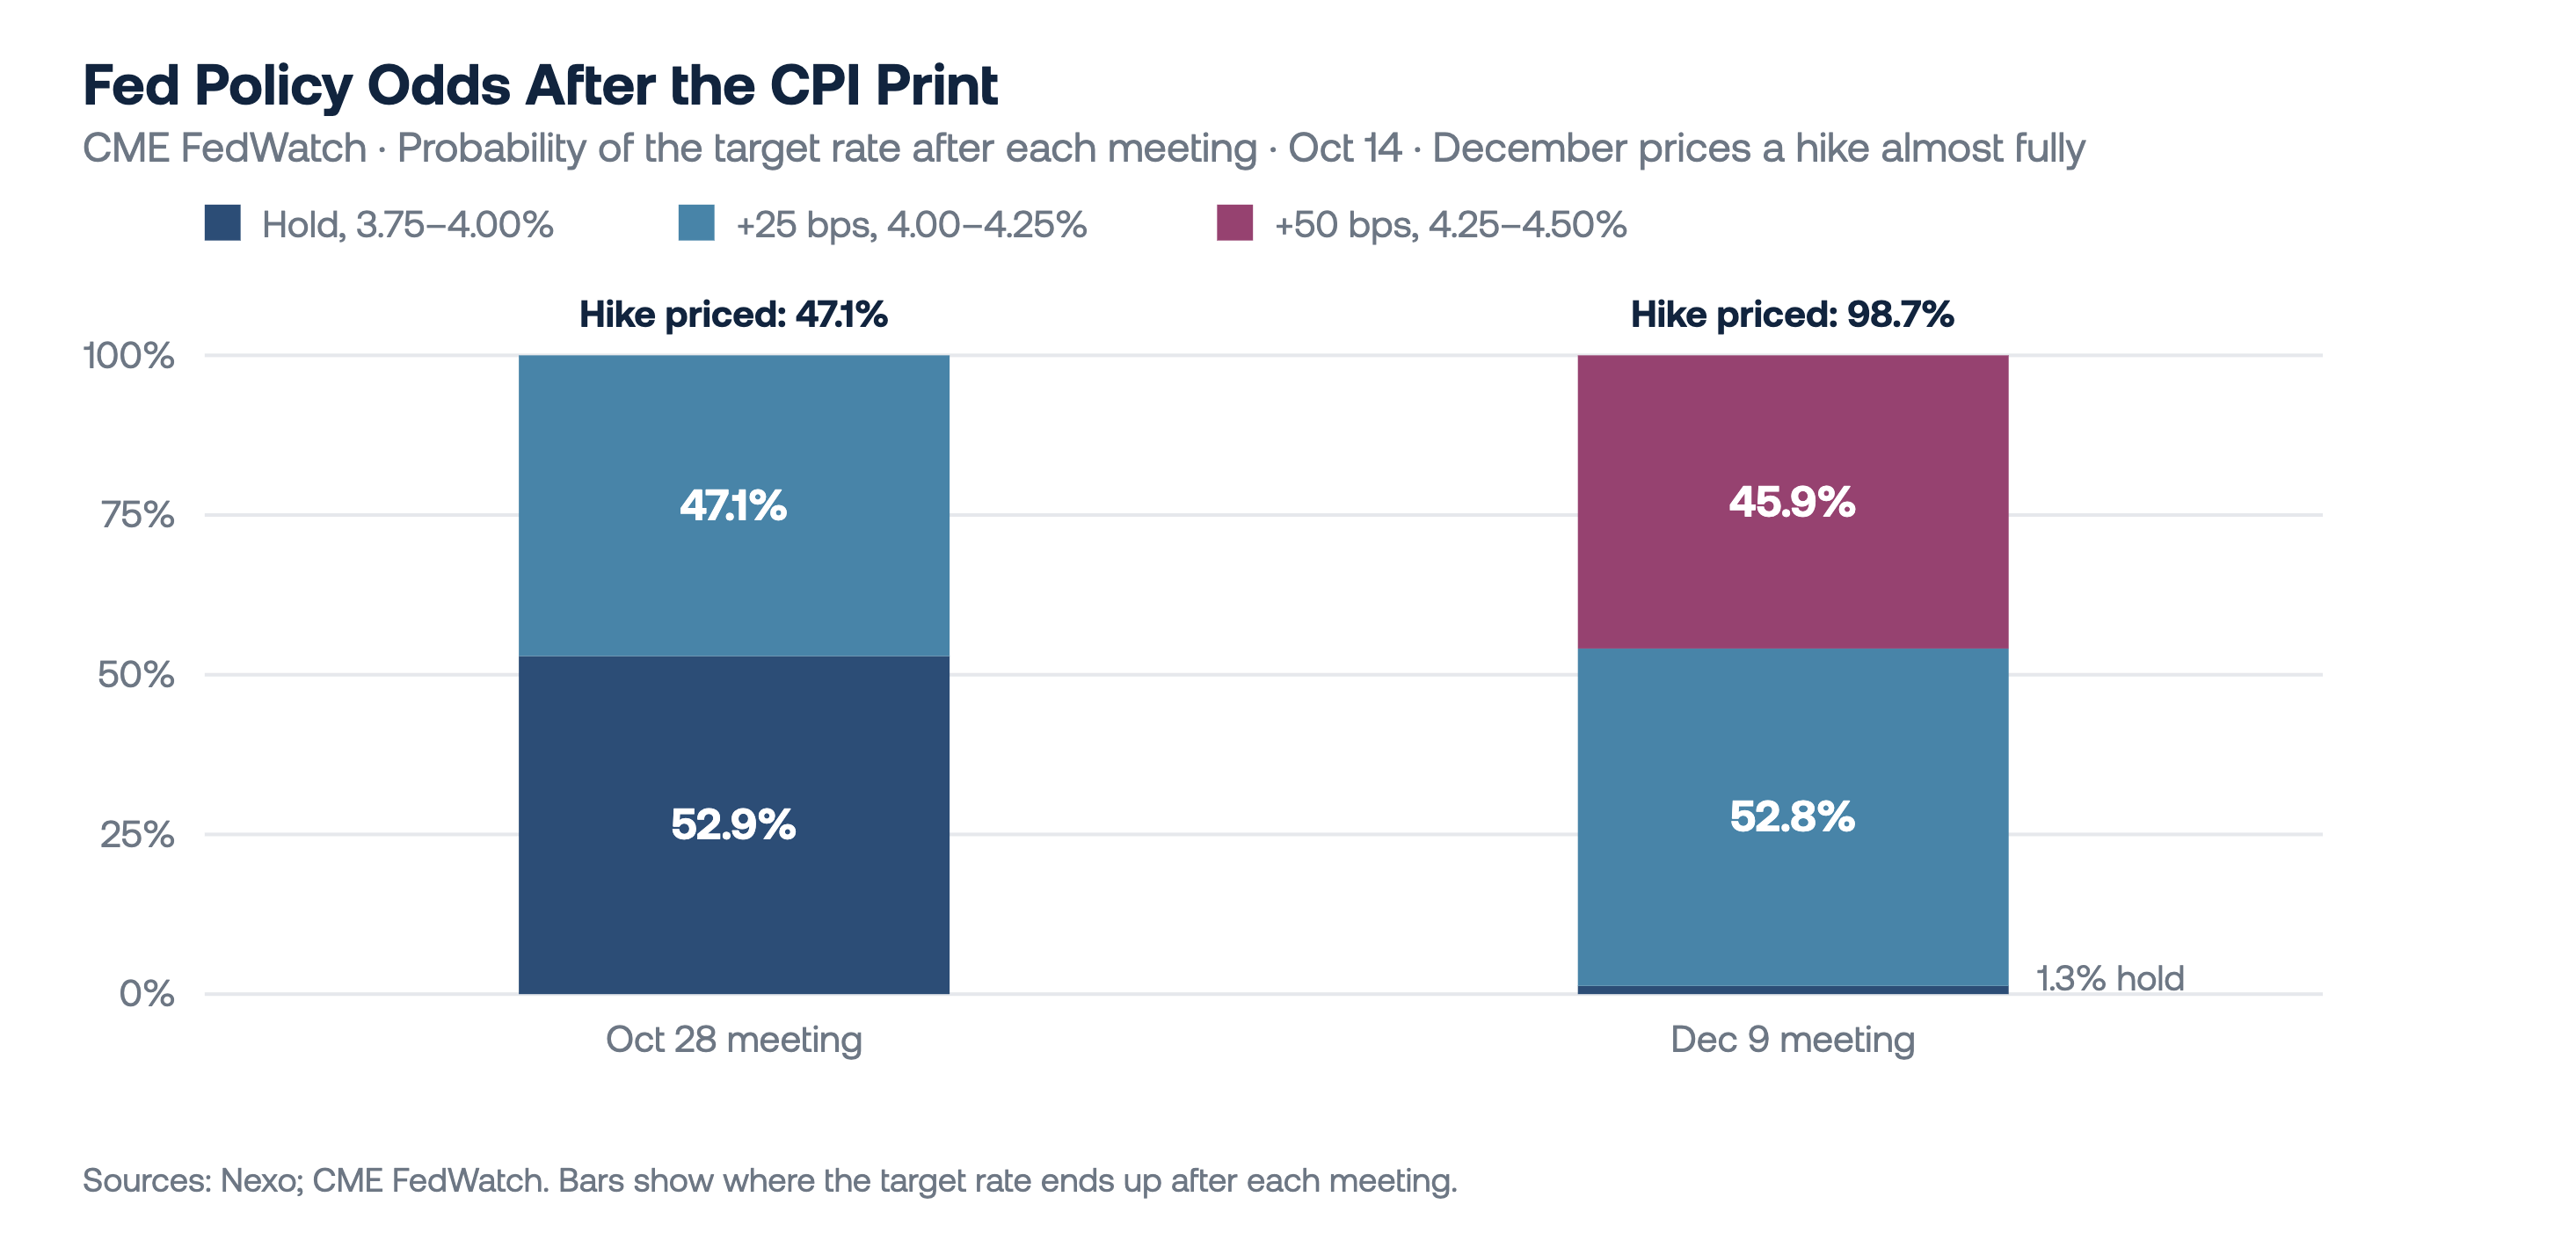
Markets are repricing for a firmer Fed after hotter-than-expected U.S. inflation: yields and the dollar are higher, while stock futures, gold and Bitcoin are lower. September CPI rose 3.7% on the year against 3.6% forecast, with core at 2.6% against 2.5%. A miss of a tenth of a point nearly doubled the odds of an October Fed hike to 43% from about 22%, leaving a hold at 57%, and a hike by December is now priced at about 95%, split roughly 55% for 25 basis points and 40% for 50 basis points, per CME FedWatch. Bitcoin fell below $83,000 and slid to $82,700 as the numbers came out. The total crypto market cap sits around $2.8 trillion. S&P 500 futures are down 0.33% at 7,779.80 and Dow futures are down 0.19% at 51,574.20, after Tuesday ended slightly lower, with the S&P 500 at 7,805.45, the Nasdaq Composite at 27,204.38 and the Dow at 51,670.10. The dollar index rose 0.5% to 102.49, gold fell about 1.5% to roughly $4,116, and the 30-year Treasury yield rose to 5.604%. Among bank earnings, Bank of America slipped premarket on a $1.2 billion provision for fines, while BlackRock rose.
Bitcoin
Bitcoin traded in a tight range before the print, then fell immediately on CPI's miss of just a tenth of a point, settling around $82,000. ETF inflows had only just resumed, with $175.6 million on Tuesday after $681 million of outflows last week, the worst since late June, per SoSoValue, and traders were already paying for downside protection. Monday’s drop reset about $771 million of leveraged positions, mostly longs. Strategy bought 250 BTC last week at an average of $86,194, lifting its holdings to 848,250 BTC.
Derivatives showed de-risking going into the report. Open interest fell about 3.5% over 24 hours alongside flat price action, meaning positions were being closed, per CoinDesk data, while the 30-day implied volatility index bounced to 40% and puts at strikes from $60,000 to $78,000 topped the options rankings.
Ethereum & Altcoins
Ether slid to $2,480 after the print, from near $2,500 before it, tracking Bitcoin lower. Before the print, Zcash led the majors near $1,270 and the rest were little changed. Speculative capital is rotating toward smaller tokens, with open interest rising in names such as NEAR and Wormhole while it declines in Bitcoin and the majors. U.S. spot Ether ETFs lost $542 million last week, and Bitmine added 12,532 ETH, lifting its treasury to about 6.03 million ETH.
Macro & Institutional
The CPI report delivered the expected rise in headline inflation but not the expected cooling in core. Core rose 0.3% on the month against 0.2% expected, and 2.6% on the year against 2.5%, up from 2.4% in August, while headline CPI rose 0.6% on the month, in line, and 3.7% on the year, from 3.4%, with energy doing the work. Each miss was a tenth of a point, so this is a slightly hotter print, not a shock, but it weakens the case that the oil shock is staying in energy. It nearly doubled the odds of an October hike and put a 50 basis point move by December in play.
Before the print, New York Fed President John Williams set a limit for the cycle, saying one more hike this year may be appropriate but that he does not expect further tightening in 2027. With two hikes by December now a live possibility, a core that failed to cool puts that view to the test. The 10-year Treasury yield, which had held near 5.20%, jumped about 6 basis points to 5.278% shortly after the print. European Central Bank President Christine Lagarde said France must fix its fiscal problems domestically rather than expect ECB backstops, and French bonds barely reacted.
Oil firmed, with Brent near $106 before the print, as Middle East tensions around Hormuz shipping and Saudi infrastructure persist, and U.S. crude is up for a fifth session.
Looking Ahead
With CPI out, attention turns to whether the Fed acts in October. Thursday’s producer price index is the first check: a firm reading would suggest the core overshoot reflects building pipeline pressure, not a one-off, while a soft one would suggest it may not persist. Retail sales and weekly jobless claims land the same day, showing whether consumers and the labor market are absorbing higher prices. Today also brings the Beige Book and remarks from Richmond Fed President Thomas Barkin and Governor Michelle Bowman, and Friday brings a speech from Fed Chair Kevin Warsh, the first chance to hear how the Chair reads the print, alongside euro-zone CPI. For Bitcoin, the $81,000 low, about $1,700 below the post-print price, is the level to watch.
Author: Iliya Kalchev, Analyst at Nexo’s Dispatch
This material is produced by Nexo for informational purposes only and does not constitute financial, investment, legal, or tax advice, or a recommendation to transact in any digital asset. Views are the author's as of the date of publication and may change without notice. Information is from sources believed reliable, but Nexo makes no warranty as to its accuracy and accepts no liability for any loss arising from reliance on this material.