Markets Today - November 5, 2026
Daily analysis of crypto markets and the forces shaping them, from the Nexo research desk.
Bitcoin eases below $78,000 as firm jobless claims reinforce Fed hike expectations, with Friday’s payrolls the next test
Bitcoin eases below $78,000 on Thursday after initial jobless claims came in below expectations, reinforcing expectations for a December Fed hike, and gives back part of Wednesday’s recovery from an early dip toward $75,700 while the wider market rebound that followed the midterms continues. U.S. futures are mixed after Wall Street’s broad rally on Wednesday, when the Dow gained 3% to 53,357.19, the S&P 500 1.6% to 7,689.58 and the Nasdaq Composite 1.4% to 25,736.51. This morning the Dow is up 0.4%, the S&P 500 is flat and the Nasdaq-100 is down 0.6% as chipmakers pause after earnings. Bitcoin remains above Wednesday’s low, which keeps most of the recovery in place even after the pullback. The 10-year Treasury yield is below 4.9%, the dollar index has eased to near 101.4, gold has extended its rebound to $4,126 and Brent has steadied near $96 after falling nearly 9% on Wednesday. Friday’s jobs report is the next test, with a December Fed hike priced at about 81% per CME FedWatch earlier today. The total crypto market cap sits around $2.6 trillion.
Macro & Institutional
The wider rebound reflects easing pressure on inflation and rates. With the midterm results adding clarity and oil lower, Brent settled on Wednesday at $94.62, its lowest since August 31, as hopes for a diplomatic resolution to the Middle East conflict grew, and cheaper energy has eased worries that the Fed would need to tighten more aggressively. Chipmakers are pausing, with Qualcomm down more than 10% premarket on weak smartphone revenue despite a strong data-center forecast, and Arm down about 4% on guidance. European shares are near record highs, with the STOXX 600 up 0.6%.
The labor market is the next test, and this morning’s data pointed to strength. Initial jobless claims fell to 189,000, below the 197,000 expected and the prior week’s 195,000, which reinforced expectations for a December hike, and private payrolls beat expectations on Wednesday. Challenger job cuts are also due today, followed by October payrolls on Friday, where steady hiring would give the Fed more headroom to tighten while softer data would ease the pressure.
Currencies and gold are settling into a more balanced pattern. The dollar has retreated from its October highs to multi-week lows as the midterm results added clarity and Treasury yields fell, but it has not broken down, since traders have kept their pricing for a December Fed hike intact, this morning’s jobless claims added support and private payrolls give it a floor, which makes Friday’s report the next test of whether the retreat extends. Citi expects the dollar to weaken against the yen over the longer term now that the midterms are over, though it sees near-term risks of yen weakness and expects Japan’s authorities to intervene if the pair tests ¥160, aiming to push it below ¥155. Gold has benefited from the softer dollar, which makes bullion cheaper for overseas buyers, and from lower yields, which reduce the cost of holding it, and it remains more than 20% below its level before the Middle East conflict began in late February, leaving room to recover if rate expectations ease.
Bitcoin
Bitcoin has recovered part of the ground lost earlier this week, rising from an early dip toward $75,700 to briefly trade above $80,000 before easing below $78,000 after jobless claims fell to 189,000, which reinforced expectations for a December hike. The reaction is a reminder that crypto remains sensitive to rate expectations, but Bitcoin is still above Wednesday’s low. Falling oil and lower Treasury yields helped the recovery, along with a broad return of risk appetite that also lifted crypto-linked equities, with Strategy and Coinbase each up about 6% on Wednesday. Miner Riot Platforms reported selling most of its Bitcoin holdings last quarter to fund its shift toward AI, supply that the market absorbed during the third-quarter rally.
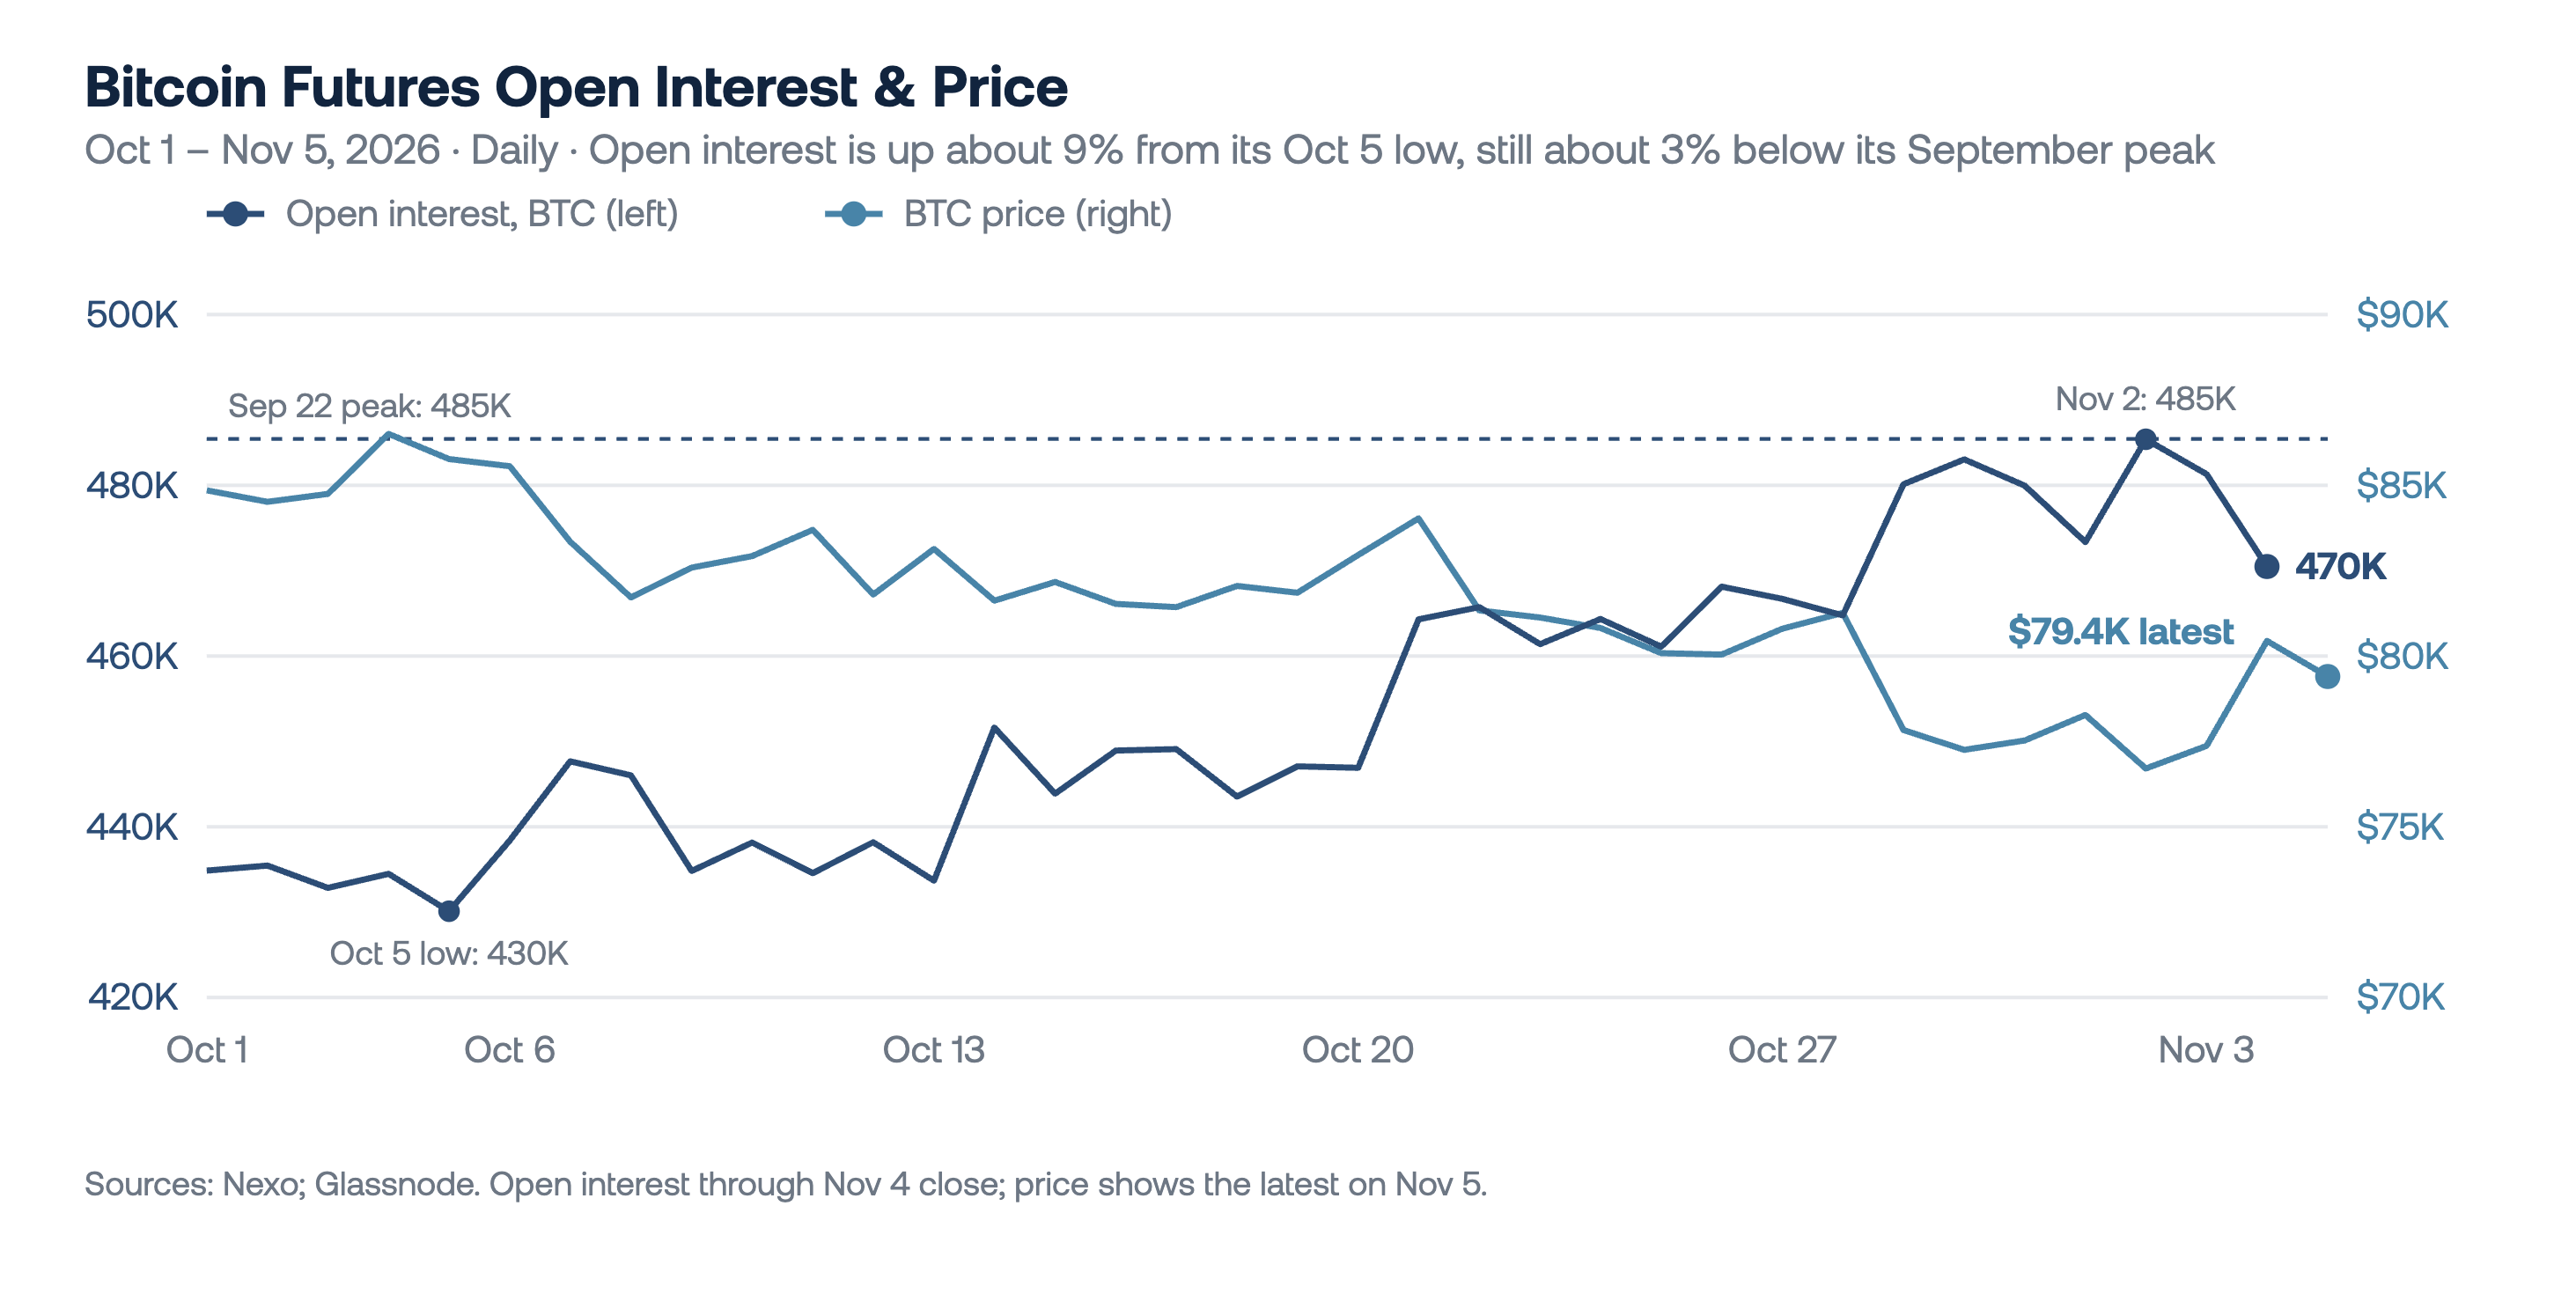
Derivatives pointed to a rally helped by short covering, with positioning rebuilding gradually behind it. Bitcoin futures open interest has recovered about 9% from its early-October low to roughly 470,000 BTC, and Ether’s has recovered to roughly 9.0 million ETH, though both remain below their September peaks, which leaves room for further rebuilding. Over the 24 hours to this morning, Bitcoin’s open interest rose only 0.3% against a 2.6% price gain, and about 93% of the $267 million of Bitcoin liquidations were shorts, so bearish positions closing did much of the work. Positioning leaned constructive as of this morning: funding was positive and slightly higher, five of the six most active Bitcoin options were calls between $78,000 and $85,000, and demand for downside protection had largely faded, with the one-week skew down to about 2% from about 11% a day earlier and one-week implied volatility near 33%.
ETF demand turned on Wednesday. U.S. spot Bitcoin ETFs took in about $75 million, per SoSoValue, ending a three-day outflow streak, and a continuation would add a further source of demand.
Ethereum & Altcoins
Ether trades below $2,350 after easing with Bitcoin on the jobless claims data, having led the majors higher on Wednesday, and XRP and Solana are also lower. U.S. spot Ether ETFs took in $53 million on Wednesday, per SoSoValue, while Ether’s options leaned defensive this morning, with four of the six most active contracts puts. Ether’s futures open interest has also rebuilt to about 9.0 million ETH, roughly 310,000 ETH above its October 13 low and about 730,000 ETH below its September peak, a sign positions are returning as price recovers.
Among altcoins, XRP reclaimed $1.30 on Wednesday as the number of wallets holding at least 1 million tokens reached 2,147, a 2026 high, up 28 in ten days and 18 in the last three, which suggests larger holders are adding during price weakness, though wallets are not the same as investors. Network activity also looks resilient, with 7,934 new XRP Ledger wallets created on November 1, its sixth-highest daily total this year. U.S. demand is more subdued, with spot XRP ETFs taking in only $18.83 million in October, the smallest monthly total since January, and a gauge of U.S. buying interest at an eight-month low, so continued accumulation is the supportive factor to watch.
Looking Ahead
Friday is the key day, with October payrolls, the unemployment rate and average hourly earnings, where steady hiring and wage growth would support the case for a December Fed hike while softer data would ease the pressure, followed by the University of Michigan survey of consumer sentiment and inflation expectations. The Fed’s next decision is on December 9. For Bitcoin, Friday’s jobs data and a continuation of ETF inflows are the signals to watch, with this morning’s reaction showing how closely crypto is tracking rate expectations.
Author: Neil Steinhardt, Head of Nexo U.S.
For informational purposes only; not financial or investment advice.
This material is produced by Nexo for informational purposes only and does not constitute financial, investment, legal, or tax advice, or a recommendation to transact in any digital asset. Views are the author's as of the date of publication and may change without notice. Information is from sources believed reliable, but Nexo makes no warranty as to its accuracy and accepts no liability for any loss arising from reliance on this material.