Markets Today - November 11, 2026
Daily analysis of crypto markets and the forces shaping them, from the Nexo research desk.
Bitcoin steadies near $73,800 as futures interest grows and CoreWeave’s results lift equity futures. Fed hike expectations are now in focus.
Bitcoin steadies near $73,800 on Wednesday after touching a three-month low overnight, as U.S. equity futures rise following CoreWeave’s third-quarter results and futures interest in Bitcoin keeps growing. Nasdaq-100 futures are up 1.5%, S&P 500 futures up 0.6% and Dow futures up 0.2%, after Tuesday’s session in which the Dow fell 0.3%, the S&P 500 0.4% and the Nasdaq Composite 0.7%, with CoreWeave’s results and a rebound in Nvidia, up about 5% premarket, leading the recovery. The U.S. bond market is closed for Veterans Day, but the 10-year Treasury yield edged up to 5.01% in Asian trading after Tuesday’s CPI, the dollar index is near 102.4, gold has steadied near $4,050 after Tuesday’s decline and Brent is near $92.
A December Fed hike is the clear base case, with a larger half-point move now priced at almost 15%, a theme that also appears in expectations for the January 27 meeting. Against that backdrop, strong AI demand has given equities a constructive tone, and Bitcoin, which has yet to join the recovery while its futures participation rises, could narrow the gap if rate expectations settle. The total crypto market cap sits around $2.4 trillion.
Macro & Institutional
Equity futures are firmer on CoreWeave’s results, which suggest AI demand remains strong. CoreWeave reported third-quarter revenue growth of 168% and raised its full-year forecast to $13 billion to $13.3 billion, above expectations, a sign that demand has held up despite concerns about policy oversight of the sector, and its shares are up more than 10% premarket after falling more than 40% over the past month, although higher interest costs widened its net loss. The lift spread across AI infrastructure names, and European chip equipment makers gained as well, with the STOXX 600 up 0.4% near a record high. OpenAI reportedly generated $10 billion of revenue in the third quarter, up nearly 50% from the prior quarter, and Anthropic’s bankers are reportedly weighing an IPO valuation of $1.5 trillion or more, above the roughly $1.4 trillion fully diluted figure implied by Tuesday’s filing.
Tuesday’s firmer CPI is still working through rates. Headline prices rose 0.4% in October and core prices 0.3%, a tenth above expectations, and Fed officials followed with firm remarks. Governor Christopher Waller said a 50-basis-point December hike should be considered if core inflation came in around 0.3% or higher, Dallas Fed President Lorie Logan said at least two more quarter-point increases are needed, and Philadelphia Fed President Anna Paulson favored continued gradual tightening. A quarter-point hike remains the base case per CME FedWatch, with a half-point move now priced at almost 15%, a theme that also appears in expectations for the January 27 meeting, the first of 2027, so the December meeting, with updated projections, is where the pace becomes clearer. Short-term Treasury yields rose by the most in 19 months on Tuesday, and bond markets abroad followed, with Japan’s 10-year yield at 2.79% after its largest daily rise since March and Germany’s near 3.31%.
The dollar index is near 102.4 after Tuesday’s 0.6% gain, with the euro near $1.1, and gold, which fell sharply on Tuesday, steadied near $4,050 after finding support around $4,000. Brent is near $92 after briefly dipping below $90 on Tuesday, as reports of incidents involving tankers in the Strait of Hormuz offset hopes for de-escalation, and market sources point to a 9 million barrel rise in U.S. crude inventories, with official data due later today.
Bitcoin
Bitcoin steadied after touching a three-month low overnight and trades near $73,800, as expectations for further Fed tightening lifted the dollar and yields, raising the opportunity cost of holding non-yielding assets. It was little changed over the past 24 hours even as Nasdaq-100 futures rose 1.5%, a gap that could narrow if rate expectations settle. Crypto-linked equities exposed to AI infrastructure did gain premarket, with IREN up 6%, Galaxy Digital up 5% and Cipher Digital up 7%, while caution around the policy outlook after the midterms continues to weigh on sentiment.
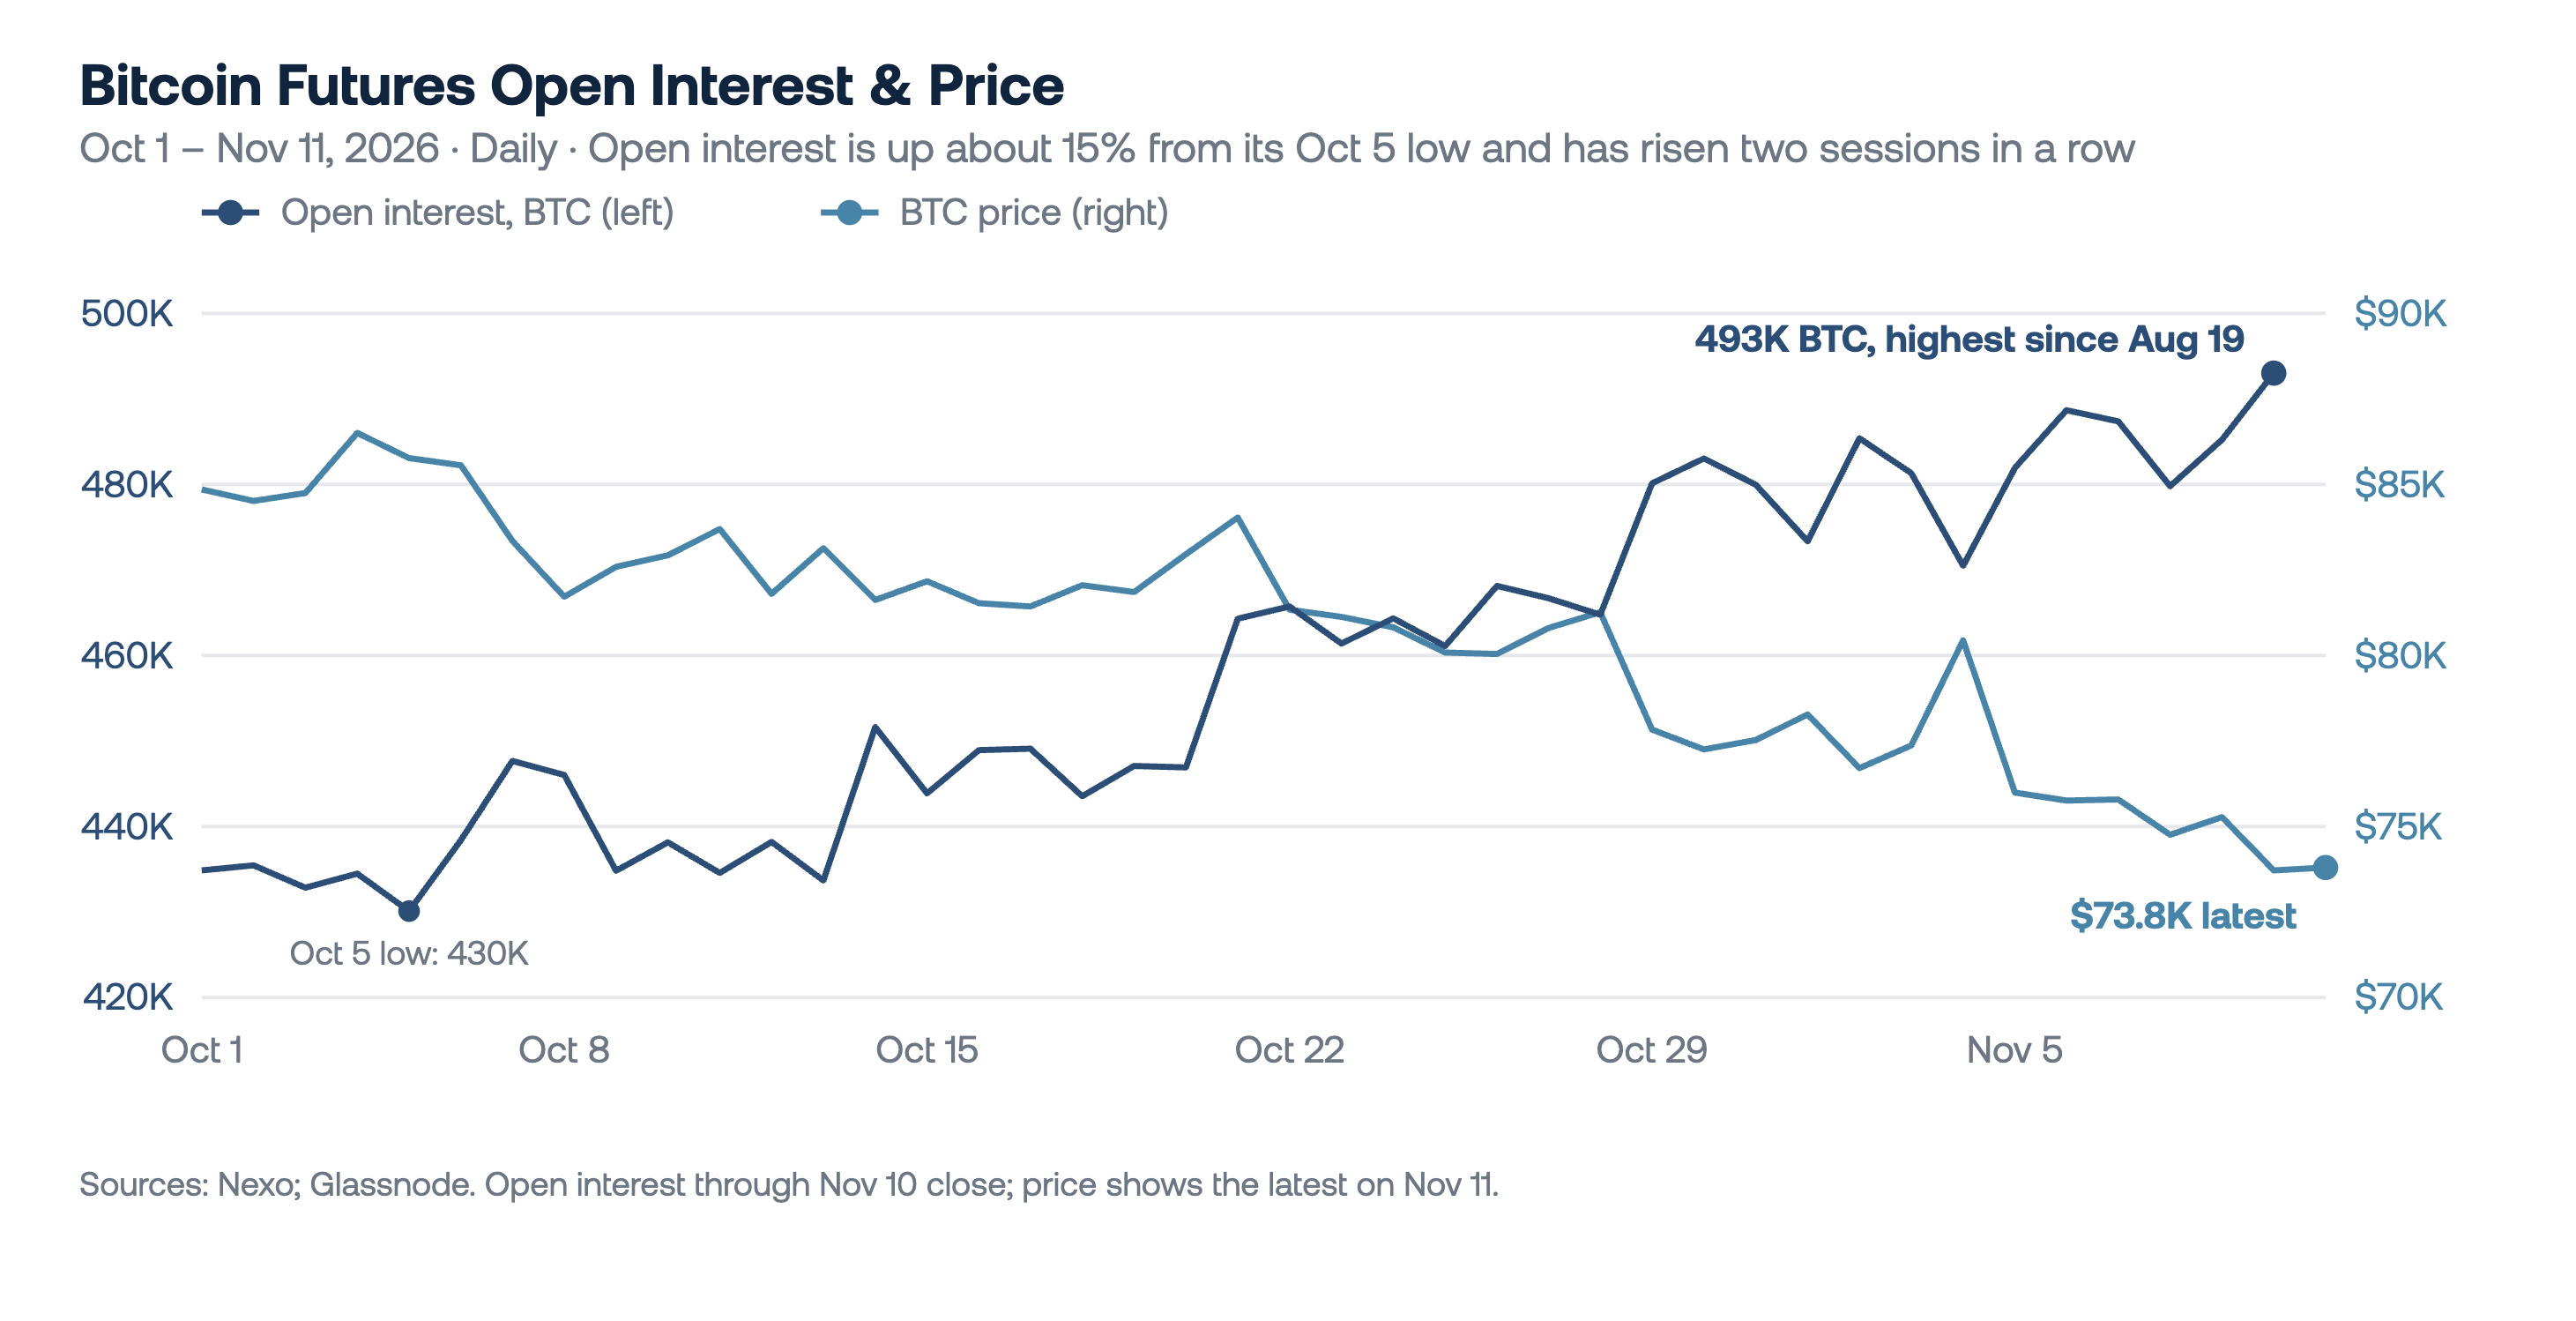
Futures interest is growing. Open interest in Bitcoin futures rose to about 493,000 BTC at Tuesday’s close, its highest since August 19 and about 15% above the October 5 low, with positions added on each of the last two sessions even as price eased. Open interest does not show direction, so the build is best read as participation returning around the Fed repricing and not as a one-way bet, but it shows the move in rate expectations has not driven traders out of the market.
ETF demand is the piece of the puzzle still to return. Outflows from U.S. spot Bitcoin ETFs continued into this week, so a return to inflows, alongside steadier rate expectations, would signal buyers coming back.
Ethereum & Altcoins
Ether trades near $2,054, XRP near $1.06 and Solana near $83, with the major altcoins easing alongside Bitcoin. Bitcoin’s share of the total crypto market has risen toward 61%, a sign of capital concentrating in the largest asset while rate expectations climb.
Ether’s supportive signals sit in staking, treasury demand and easing ETF outflows. Bitmine bought 9,500 ETH last week, lifting its holdings to about 6 million ETH, within roughly 35,000 ETH of its self-imposed supply ceiling, with most of the position staked, and it has said purchases will stop once it reaches that level, which will shift attention to other sources of demand. Close to one million ETH is reportedly waiting to enter staking against only about 4,300 waiting to leave, which points to holders committing coins to the network. ETF outflows have slowed sharply, with U.S. spot Ether ETFs seeing about $365 million of outflows last week. There is an important trend beneath this number: $185 million of outflows came on Monday, followed by only $1.3 million on Tuesday, so a return to inflows would be the next sign of buyers coming back.
Looking Ahead
Today, the U.S. bond market is closed for Veterans Day while stocks trade, and official crude inventory data is due later. Thursday brings U.S. jobless claims, a check on the labor market after last week’s strong payrolls. A 30-year Treasury auction, the first since the holiday, will test demand with the 10-year yield near 5%. Cisco and Applied Materials report earnings, the next reads on AI infrastructure demand. Friday brings October producer prices, the second inflation check after CPI. The Fed’s next decision is on December 9, followed by the first meeting of 2027 on January 27, where expectations for further tightening are also building. For Bitcoin, Friday’s producer prices and a return to ETF inflows are the signals to watch, with growing futures participation a supportive backdrop.
Author: Neil Steinhardt, Head of Nexo U.S.
For informational purposes only; not financial or investment advice.
This material is produced by Nexo for informational purposes only and does not constitute financial, investment, legal, or tax advice, or a recommendation to transact in any digital asset. Views are the author's as of the date of publication and may change without notice. Information is from sources believed reliable, but Nexo makes no warranty as to its accuracy and accepts no liability for any loss arising from reliance on this material.