Markets Today - September 30, 2026
Sep 30•4 min read
Daily analysis of crypto markets and the forces shaping them, from the Nexo research desk.
Bitcoin spikes above $85,000 before reversing towards $83,000 as cooler PCE cuts October Fed hike odds
Bitcoin trades near $83,500 on Wednesday after a softer-than-expected U.S. inflation report strengthened the case for the Federal Reserve to pause in October. Core PCE rose 0.2% month-on-month in August and 3.0% year-on-year, below expectations, while headline PCE increased 0.3% and 3.4%, respectively. The surprise has pushed the implied probability of an October rate hike down to roughly 37%. U.S. equities are modestly higher in response, with the S&P 500 up around 0.3%, the Nasdaq 0.4% and the Dow 0.2%, while Treasury yields have eased slightly. Gold has moved higher toward $4,200 and Brent trades around $97. The important combination is cooler inflation without a growth scare: second-quarter GDP was revised up to 2.2% and August consumer spending surged 0.9%.
Bitcoin
Bitcoin trades near $83,500, still below last week's eight-month high near $87,400 but on course for a roughly 42% gain in the third quarter – its strongest quarterly performance since late 2024. Price remains around the $81,000-$86,000 long-term holder supply zone, with the heaviest concentration near $84,000-$85,000. The softer inflation print removes some of the immediate macro pressure, but BTC's muted initial reaction suggests the next leg higher still needs fresh crypto-native demand.
On-chain data points to a market cooling after the rally. Short-term traders' unrealized profit margin has reached 33%, its highest since December 2024, while holders realized 25,700 BTC in profits on September 22, the largest single-day total this year. Spot demand has contracted by 170,000 BTC over the past month, while futures demand growth slowed sharply into quarter-end.
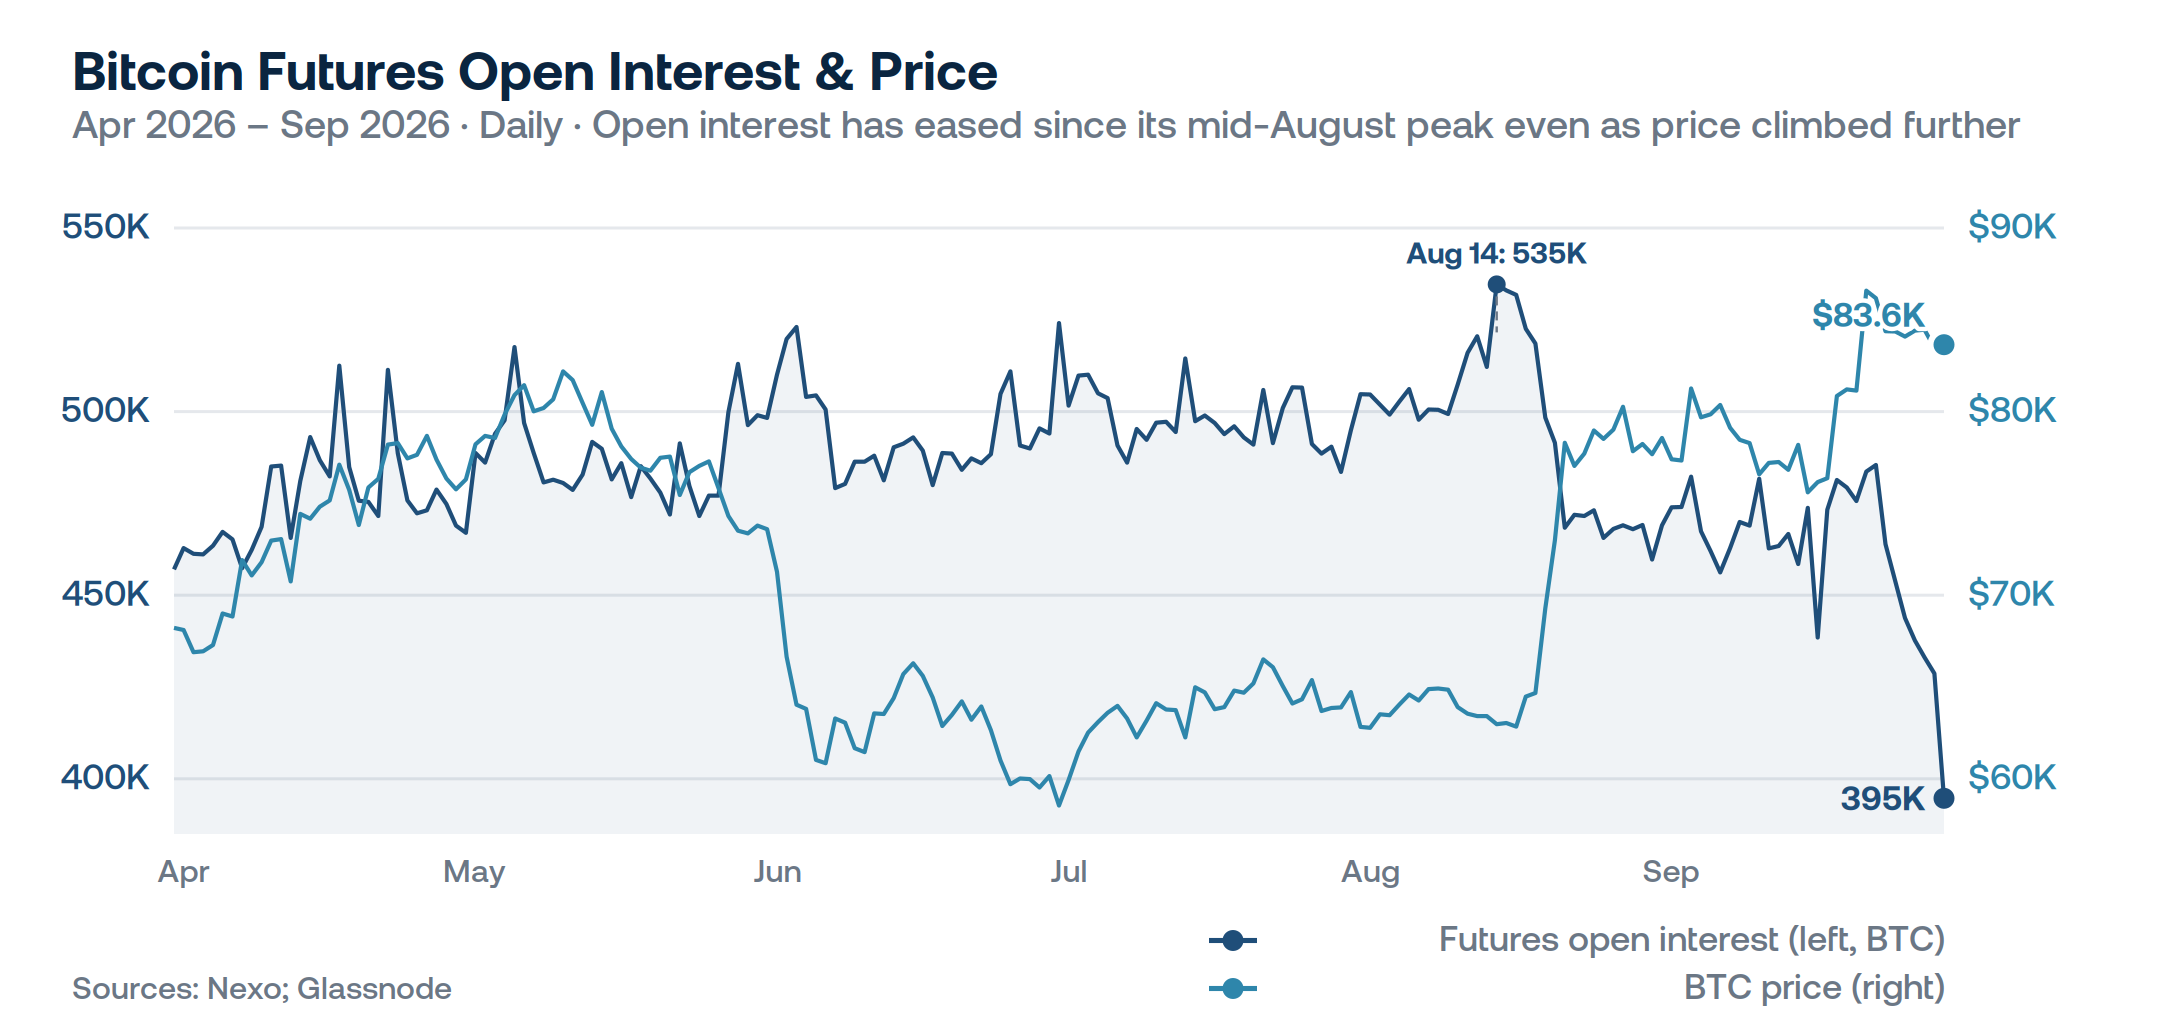
The leverage picture is more constructive. Coin-denominated futures open interest has fallen to its lowest since March and sits almost 20% below August levels, with perpetual positioning close to neutral. The rally has lost some demand, but it has also lost much of its leverage – leaving spot buyers, rather than speculative positioning, to determine the next move.
Ethereum & Altcoins
Ether trades near $2,670 and remains on course for a nearly 70% third-quarter gain, comfortably ahead of Bitcoin. XRP is set to finish the quarter roughly 44% higher and BNB around 39% higher. Some profit-taking pressure is emerging, with seven-day altcoin inflow transactions to exchanges reaching their highest level since October 2025.
Institutional access continues to expand despite the softer near-term momentum. Bitwise has launched the first U.S. spot ETF providing direct exposure to NEAR, trading on NYSE Arca, with staking rewards set to accrue to shareholders through the fund's NAV. The expansion of single-asset ETFs beyond the largest tokens suggests institutional crypto infrastructure is broadening even as market momentum cools.
Macro & Institutional
Wednesday's data weakened the case for an immediate follow-up Fed hike. Core PCE rose 0.2% month-on-month versus 0.3% expected and held at 3.0% year-on-year, while headline PCE also undershot expectations at 0.3% monthly and 3.4% annually. Markets now put the probability of an October increase at roughly 37%, down from around 75% only a day earlier. Treasury yields have eased modestly, although the 10-year remains near historically elevated levels after September's sharp selloff in bonds.
The growth side of the release complicates the picture in a constructive way. Second-quarter GDP was revised up to an annualized 2.2% from 1.5%, while consumer spending jumped 0.9% in August. In other words, the Fed received softer inflation without obvious evidence that demand is breaking. Lower inflation gives policymakers more room to wait; resilient growth gives them less reason to rush in either direction.
Treasury yields remain the central macro constraint. The U.S. 10-year yield is holding near 5.23%, around its highest level since 2007 and up nearly 50 basis points in September. Yet expectations for an immediate follow-up Fed hike have shifted dramatically: markets now put the probability of an October increase at roughly 49%, down from around 75% a day earlier after softer labor data and Williams' comments.
Energy pressure has eased at the margin. Brent trades near $103 after falling 2.6% Tuesday as Saudi Arabia restored flows through its East-West pipeline to at least 3.5 million barrels per day, providing an alternative route around the Strait of Hormuz. It nevertheless remains on course for a roughly 14% monthly gain. Lower oil offers some inflation relief; yields near two-decade highs show the broader tightening pressure has hardly disappeared.
Looking Ahead
With PCE now behind markets, attention shifts toward activity and employment. Thursday brings Eurozone unemployment and the U.S. S&P Global and ISM manufacturing PMIs. Friday then delivers the week's other major test: September nonfarm payrolls, unemployment and average hourly earnings, alongside preliminary Eurozone inflation.
The question has shifted from whether inflation would force another immediate hike to whether the labor market is strong enough to keep one on the table later this year. For Bitcoin, the macro hurdle has eased, but the muted response to a favorable inflation surprise reinforces the importance of spot demand. Holding the $80,000-$85,000 area would preserve the broader structure established during the third-quarter rally, while a return above $87,000-$88,000 would put the recent highs back in play.
Author: Iliya Kalchev, Analyst at Nexo’s Dispatch
This material is produced by Nexo for informational purposes only and does not constitute financial, investment, legal, or tax advice, or a recommendation to transact in any digital asset. Views are the author's as of the date of publication and may change without notice. Information is from sources believed reliable, but Nexo makes no warranty as to its accuracy and accepts no liability for any loss arising from reliance on this material.