Markets Today - September 14, 2026
Sep 14•5 min read
.png)
Daily analysis of crypto markets and the forces shaping them, from the Nexo research desk.
Bitcoin holds firm near $78,000 as Fed hike odds surge past 85% into a pivotal week
Bitcoin trades near $78,000 on Monday, up modestly after last week's roughly 3% decline, holding steady even as U.S. equity futures point sharply lower, with the Nasdaq 100 down more than 1.5% and the S&P 500 and Dow both softer after prominent AI industry voices called over the weekend for a slower pace of frontier model development. The more consequential story for markets broadly is how quickly the case for a Federal Reserve rate hike has hardened: futures markets now price better than an 85% probability of a quarter-point increase at Wednesday's decision, up from levels closer to 60% just a few sessions ago. Oil has surged toward $110 a barrel as Middle East shipping disruptions worsen and a planned Iran-Gulf meeting was postponed, adding a fresh inflationary impulse just as the Fed's decision comes into view. Ether trades near $2,500, and the broader altcoin complex has posted its broadest daily advance in two weeks.
Bitcoin
Bitcoin trades near $78,000, up modestly Monday and largely unmoved by the broader equity selloff. With no crypto-specific catalyst behind the move, that steadiness looks less like conviction buying and more like the market treating crypto as insulated from the pressures weighing on other risk assets today. Sentiment around the long-delayed Clarity Act has offered a modest, more crypto-specific tailwind: prediction markets now price roughly a 30% chance the bill becomes law this year, up from just 12% at the start of September, ahead of a procedural Senate vote Tuesday.
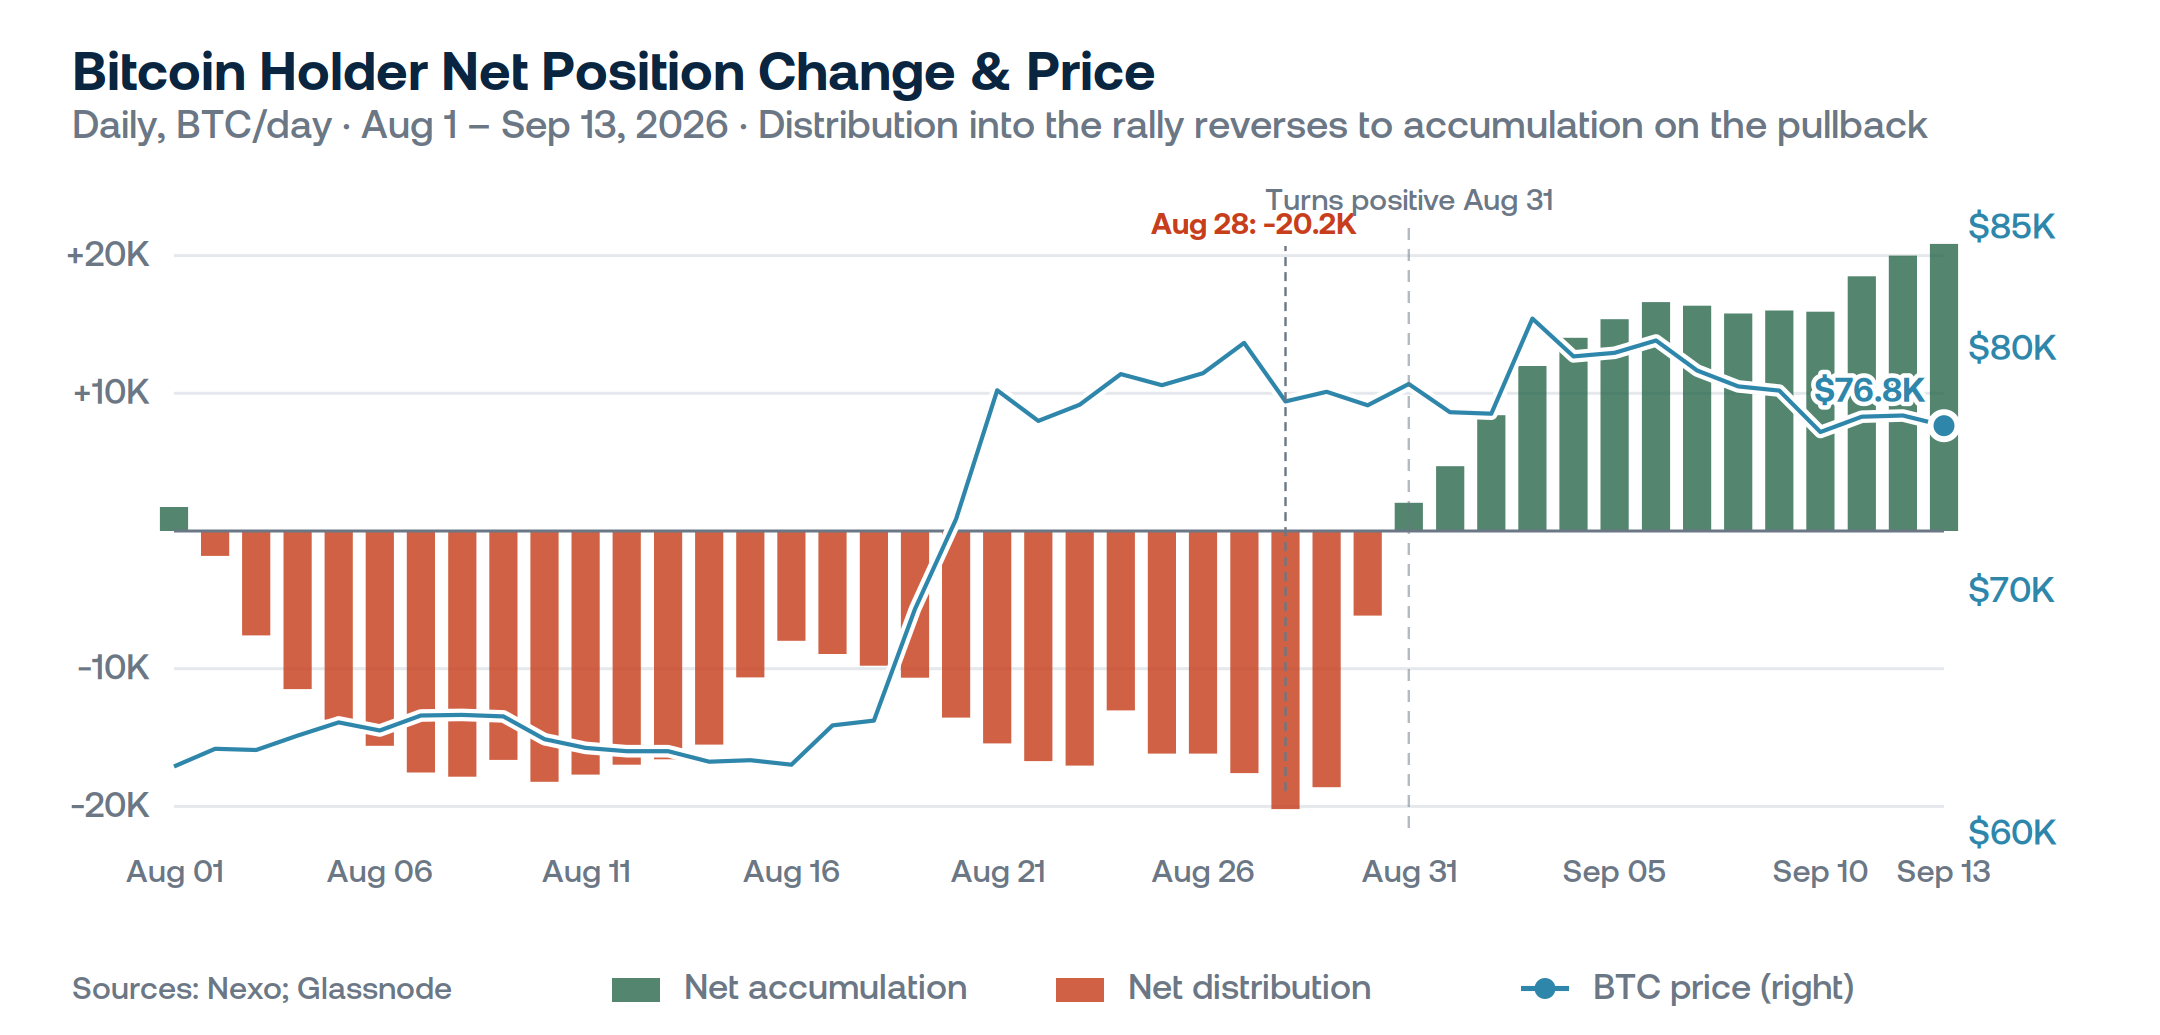
The more revealing story sits in how long-term holders have behaved through this pullback. Net position change among this cohort bottomed at -20,182 BTC per day on August 28, as holders sold steadily into the rally that carried price from the low $60s toward $80,000. That reversed sharply at month-end: net position change turned positive on August 31 and has climbed in nearly every session since, reaching +20,843 BTC per day by September 13, even as spot pulled back from its September 3 high of $81,262 to under $77,000. The seven-day average has swung to +17,632, a sharp reversal from the -732 thirty-day average that August's selling still weighs on. The cost-basis data explains why: the heaviest concentration of holder cost basis in the current range sits at $75,426, just below spot, while the $82,814 ceiling above has barely moved in a month. Holders sold into the rally on the way up, and now that price has pulled back to roughly where most of them actually bought, they are accumulating again rather than capitulating – a meaningfully different dynamic than a market simply running out of buyers.
Derivatives positioning leans constructive too: open interest is rising, funding rates are positive, and the long-to-short account ratio favors longs, while futures basis on both major exchanges runs well above the current fed funds rate – a spread that reflects genuine bullish carry rather than defensive positioning. Liquidations, meanwhile, ran at roughly half Friday's pace, consistent with a market grinding higher rather than being squeezed.
Ethereum & Altcoins
Ether trades near $2,500, and XRP has advanced further, leading a broad-based move that lifted nearly every token in the sector's largest composite index Monday – the widest daily advance in two weeks. Solana, Cardano, and BNB have all firmed more modestly. Ether's own derivatives market echoed Bitcoin's: open interest rose nearly 3% to $14.8 billion, alongside rising funding rates consistent with the broader shift toward long positioning across the sector.
The more telling story sits in last week's flows: U.S. spot Bitcoin ETFs saw $463 million in outflows over four sessions, ending their strongest inflow run of the year, while spot Ether ETFs pulled in $197 million over the same stretch – a genuine rotation between the two largest assets, not just Ether holding up better on its own.
Macro & Institutional
The path to Wednesday's Fed decision has moved with unusual speed. A week ago, markets were debating whether a hike would happen at all; by Monday, the probability implied by futures markets had climbed above 85%, and attention has shifted to whether Chair Kevin Warsh signals a single, one-off move or the start of a broader tightening campaign when he addresses reporters after the decision alongside the Fed's updated economic projections. That repricing followed Friday's CPI report, where core inflation rose a hotter-than-forecast 0.3% on the month, briefly pushing the 10-year Treasury yield above 5% for the first time in nearly three years. One bank has already added a third hike to its forecast, now expecting the Fed to deliver 75 basis points of tightening in total across September, December, and March – effectively unwinding last year's rate cuts in full. Equity strategists remain split on the implications: some argue a shallow hiking cycle is manageable given strong earnings growth, while others caution that further Middle East escalation, rather than the rate path itself, is the more meaningful risk to markets from here.
That geopolitical risk intensified over the weekend. A planned meeting between Iran and Gulf states aimed at restoring shipping through the Strait of Hormuz was postponed at Saudi Arabia's request, removing a de-escalation catalyst that had helped ease oil prices last week. Iran-aligned Houthi forces have since expanded their reach in the Red Sea, and the closure of a key Saudi pipeline threatens to remove several percent of global oil supply if it isn't restored within days. Brent has surged toward $110 a barrel as a result, extending a nearly 9% weekly gain and feeding directly into the same inflation concerns driving this week's rate repricing. Gold has fallen on the combination of a stronger dollar and higher rate expectations, even as its longer-term safe-haven case, tied to geopolitically driven rather than demand-driven inflation, remains intact by most accounts. The dollar has climbed to a two-week high, while the yen – still near seven-month highs and up roughly 4% this month – has speculators net long for the first time since February, ahead of a widely expected Bank of Japan hike Friday.
Looking Ahead
Wednesday is the week's pivot point: the Fed's rate decision, updated economic projections, and Chair Warsh's press conference all land alongside U.S. retail sales data, and the UK inflation report rounds out the day's calendar. Thursday brings the Bank of England's decision – a hold at 3.75% is expected – alongside Eurozone CPI, weekly jobless claims, and the Philadelphia Fed manufacturing index. The Bank of Japan closes out the week Friday, widely expected to raise its own rate to 1.25%, with ECB President Lagarde also due to speak. For Bitcoin, the $75,426 cost-basis cluster just below spot is now the level to watch for support, while the $82,814 ceiling above marks the more immediate resistance standing between here and a fresh push higher.
Author: Iliya Kalchev, Analyst at Nexo’s Dispatch
This material is produced by Nexo for informational purposes only and does not constitute financial, investment, legal, or tax advice, or a recommendation to transact in any digital asset. Views are the author's as of the date of publication and may change without notice. Information is from sources believed reliable, but Nexo makes no warranty as to its accuracy and accepts no liability for any loss arising from reliance on this material.