Markets Today - October 2, 2026
Oct 02•4 min read
.png)
Daily analysis of crypto markets and the forces shaping them, from the Nexo research desk.
Bitcoin eyes $87,000 as softer labor market pushes Fed hold odds above 80%
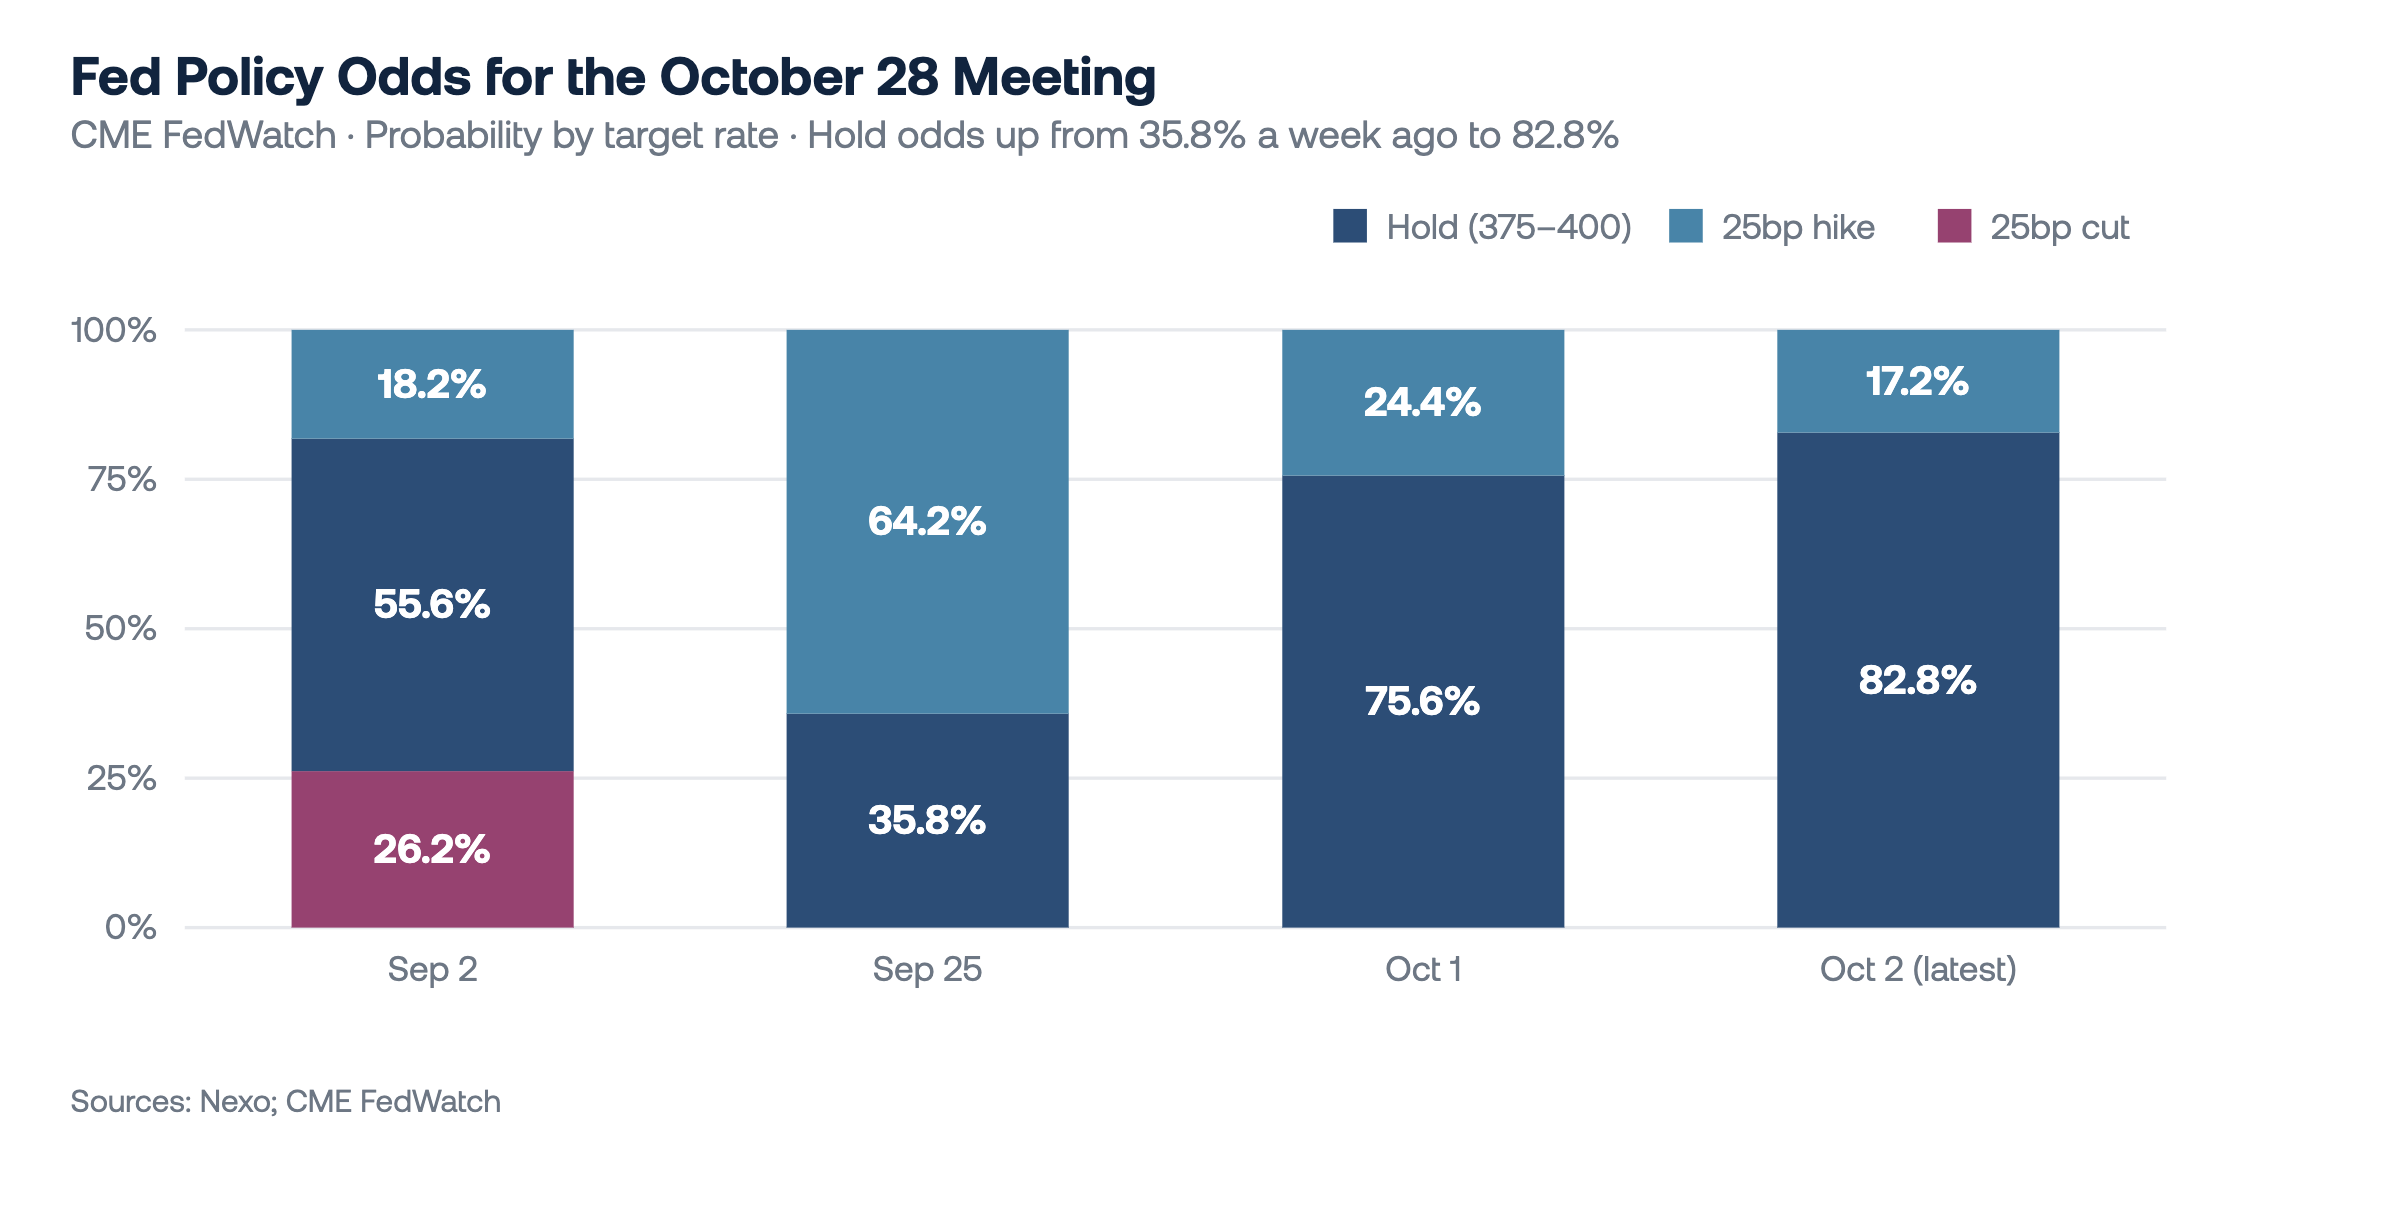
Inflation cooled earlier this week, with core PCE softening though still above the Fed's 2% target, and today's jobs report delivered another dent in the case for further hikes. Nonfarm payrolls rose just 29,000 against a forecast of 89,000, well below August's initially reported 162,000, while unemployment ticked up to 4.2% from 4.1% and average hourly earnings rose 0.1% against 0.3% expected, softer readings on both sides of the Fed's dual mandate. Bitcoin pushed toward $87,000 as the data landed before settling just above $86,500, on track for a third straight weekly gain, with the total crypto market cap around $2.9 trillion. CME FedWatch put the odds of a hold at the October 28 meeting at 71.8% on Friday, with a 28.2% chance of a hike, roughly double the 35.8% hold probability a week earlier. U.S. equity futures sharply extended gains on the data, with S&P 500 futures up 0.9%, Nasdaq-100 futures up 1.2% and Dow futures up 1.0%, as Treasury yields eased and oil fell and investors read the numbers as giving the Fed room to hold rather than tighten.
Bitcoin
Bitcoin climbed from about $83,500 at the end of September to just below $87,000 as the report was released, then eased back to settle just above $86,500. It is up 6.4% in September, its third straight monthly gain, and sits within about 1% of where it started 2026 after bottoming near $58,000 over the summer. Spot Bitcoin ETFs returned to inflows on Thursday with about $102 million, after Wednesday's outflow ended a nine-day streak. Bitcoin's share of the total crypto market is closing in on 60%, while USDT's share has slipped to about 6.3%, a sign traders were moving from cash into tokens, per CoinDesk data.
Positioning had been built for a softer rate outlook. Open interest rose to about 653,000 BTC ($56.2 billion) from 626,000 on September 30, per CoinGlass, and perpetual funding moved from around 3% to about 10% annualized. Calls made up 88% of options volume, and about $344 million of leveraged positions were reset over 24 hours, mostly shorts. Open interest was near a 12-month low at the end of September, so this was a rebuild rather than a crowded trade. A soft print fits that setup, though richer funding means positioning is sensitive to any change in direction.
Ethereum & Altcoins
Ether traded near $2,750 before the release, firmer on the day. U.S. spot Ether ETFs lost just over $110 million across Tuesday through Thursday, a quiet divergence from Bitcoin's return to inflows. XRP, Solana, Cardano and BNB all rose, though none kept pace with Bitcoin. The sharper moves came further down the market-cap list.
Macro & Institutional
The report cuts at both halves of the Fed's dual mandate. Hiring slowed sharply, unemployment edged up, and wage growth cooled to 0.1%, easing one of the worries that had kept hike talk alive. It also diverged from the data earlier in the week, which pointed to resilience: initial jobless claims fell to 197,000, near historic lows, continuing claims dropped to 1.701 million, the lowest since March 2023, and ADP reported 90,000 private jobs. Low layoffs alongside slower hiring suggest a cooling labor market rather than a deteriorating one.
Much of the repricing came before the release. Hold odds had already reached 75.6% on Thursday, so the report confirmed the pause case more than it extended it. The Fed's own debate had not settled either. Dallas Fed President Lorie Logan said rates need to rise at least another 50 basis points, though she noted the surge in yields can slow the economy and reduce the need for tightening, in effect the bond market doing part of the Fed's work. Minneapolis Fed President Neel Kashkari expects more hikes into 2027 but is unsure about October. One report leaves the later path open.
Treasury yields backed off after the release. Before it, the 10-year stood near 5.23% after touching 5.344% on Thursday, its highest since 2002, and the dollar index sat near a 17-month high above 102. Euro-zone inflation rose to 3.8% in September from 3.2%, above the 3.6% expected, keeping the case for further ECB tightening in play. Gold traded near $4,187, heading for a second weekly decline. Brent's December contract fell 2.7% to about $99.50, easing after Thursday's jump on reports of additional U.S. military deployments to the Middle East.
Looking Ahead
The lead event next week is Wednesday's minutes from the Fed's September meeting, which delivered the hike. Officials have been split on how far tightening should go, so the minutes should show how broad the support for further hikes was, even as softer jobs data has shifted market pricing. Monday's ISM services survey adds a read on employment and prices, Thursday's initial jobless claims, last at 197,000, will show whether slower hiring is turning into layoffs, and Wednesday's 10-year note auction tests demand after the yield touched its highest since 2002 this week. The October 14 CPI report is the next major inflation test, ahead of the Fed's October 28 meeting. For Bitcoin, the 10-year real yield and the $87,400 level just above spot are the markers to track.
Author: Iliya Kalchev, Analyst at Nexo’s Dispatch
This material is produced by Nexo for informational purposes only and does not constitute financial, investment, legal, or tax advice, or a recommendation to transact in any digital asset. Views are the author's as of the date of publication and may change without notice. Information is from sources believed reliable, but Nexo makes no warranty as to its accuracy and accepts no liability for any loss arising from reliance on this material.