Markets Today - October 16, 2026
Oct 16•4 min read
.png)
Daily analysis of crypto markets and the forces shaping them, from the Nexo research desk.
Bitcoin rebounds above $82,000 after a two-hour dip below $80,000, but heads for a second weekly loss
Bitcoin trades near $82,200 on Friday, recovering after a brief dip below $80,000 as lower Treasury yields and oil and a rebound in Asian chip stocks aided risk appetite, though it is still on course for a second straight weekly loss. The total crypto market cap sits around $2.8 trillion. U.S. futures are mixed, with the Dow up 0.4%, the S&P 500 up 0.2% and the Nasdaq-100 down 0.1%, after Thursday’s rebound lifted the S&P 500 0.3% to 7,744.81, the Nasdaq Composite 0.1% to 26,713.03 and the Dow 1.1% to 52,177.81. For the week, the Nasdaq is down more than 2% and the S&P 500 almost 1%, while the Dow is on pace for a gain of about 1%. Tesla is up 4.4% premarket after unveiling a redesigned Roadster, while CoreWeave, the AI data-center operator at the center of this week’s rout, is down 4.1% and Micron 1.7%. In Asia, the Kospi rose nearly 3%, and the Stoxx 600 is up 0.6%. The 10-year Treasury yield is near 5.07%, its lowest since late September, the dollar index is about 101.8 and heading for its first weekly decline in five weeks, and spot gold is at $4,187.66. CME FedWatch shows roughly a 28% chance of an October hike, with a quarter-point hike in December the market’s base case.
Bitcoin
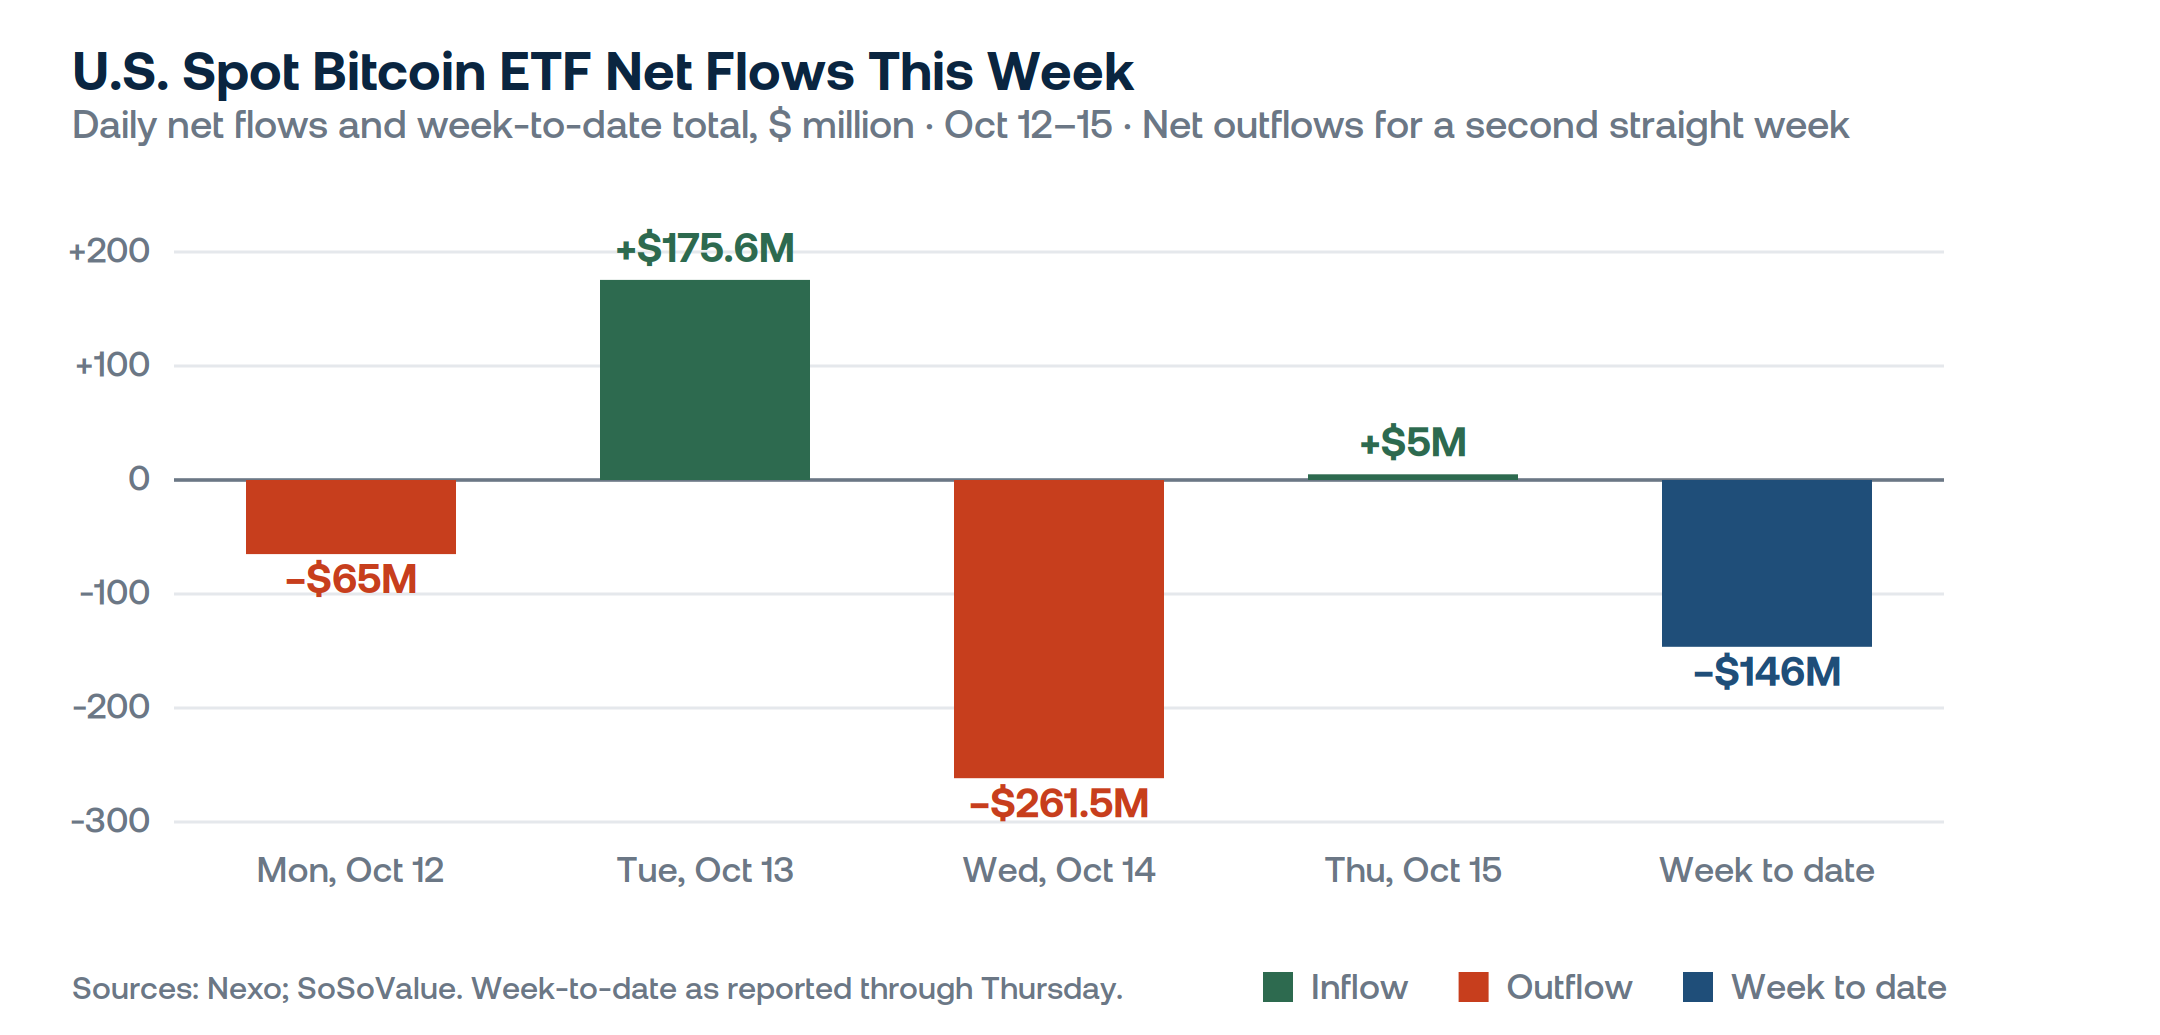
Bitcoin’s break below $80,000 lasted about two hours. Thursday’s slide took it to roughly $79,800, through the $80,400 low that buyers had defended twice in the past week, and buyers stepped in there for a third time, lifting it back near $82,500 and holding above $81,000 through Asian trading. A push back above $84,000, where Wednesday’s post-CPI spike ran out of steam, would show the bounce has real buyers behind it. So far the flows lag the price: spot Bitcoin ETFs took in a thin $5 million on Thursday after Wednesday’s $261 million exit, leaving about $146 million of outflows for the week and a second straight week of withdrawals, per SoSoValue. Bitcoin is down about 0.9% on the week and over 2% in October, as the usual October strength has failed to appear for a second year running, and a second straight day of ETF inflows would be the first sign of demand returning.
Ethereum & Altcoins
Ether trades near $2,450, bouncing with Bitcoin but still lower on the week, while Zcash led the majors, rising to about $1,230, and Solana trades near $106, with XRP, Cardano and BNB also firmer. Altcoin ETFs show the same lag: the U.S. Zcash fund lost about $15 million on Thursday, its fifth outflow this month, Ether funds shed about $60 million, Solana funds lost nearly $10 million, their ninth straight day of withdrawals, and XRP funds saw a small outflow.
Macro & Institutional
Fed Chair Kevin Warsh, speaking in Bangkok, gave no signal on the October 27 to 28 meeting, saying he does not prejudge meetings, but described the U.S. economy as more resilient than he expected and said his talks with other central bankers show the same surge in prices. He framed AI as boosting demand before it lifts supply, a positive supply shock in the medium term but a bumpy transition for policymakers, and markets took the lack of hawkishness as good news, with October hike pricing falling. Thursday’s data had been hot, with producer prices up 1.3% in September, the most since March 2022, core producer prices up 0.7% against 0.3% expected, retail sales up 0.8% against 0.3% expected, and jobless claims steady at 199,000. October hike odds briefly rose to nearly 34% before falling back to around 27% as bonds rallied.
Government bonds are regaining haven status even with inflation running hot. Treasuries rallied for a second day, G7 bonds are on track for their strongest week since late May, and German Bund yields have turned positively correlated with stocks for the first time since August, as investors worry about the financing behind the AI buildout. CoreWeave is down more than 15% on the week, and some Anthropic investors are reportedly discussing a valuation near $1.5 trillion, down from about $2 trillion, after its third-quarter revenue growth slowed to 45%, though TSMC’s record quarterly profit shows demand is intact. The market’s pushback on AI-linked debt is likely to slow capital spending, which favors firms that fund data centers from operating cash flow.
Oil is firmer on the week, with Brent near $105 and WTI near $97, as Middle East shipping tensions and a large U.S. inventory draw outweigh a report that Washington is weighing easing sanctions on some tankers. The International Energy Agency agreed to release over 20 million barrels of diesel.
Looking Ahead
Next week is the last full week of data before the Fed’s October 27 to 28 meeting. Monday brings China’s third-quarter GDP. Wednesday brings UK September CPI and a U.S. 20-year bond auction. Thursday brings U.S. jobless claims, and Friday brings the U.S. flash PMIs and the University of Michigan consumer survey. A hold is priced at roughly 72% for the Fed’s meeting, with core PCE on October 29 and payrolls on November 6 to follow. For Bitcoin, a move back above $84,000 and a second day of ETF inflows are the signs buyers are returning, with the $80,000 area, defended three times in a week, the level to hold.
Author: Iliya Kalchev, Analyst at Nexo’s Dispatch
This material is produced by Nexo for informational purposes only and does not constitute financial, investment, legal, or tax advice, or a recommendation to transact in any digital asset. Views are the author's as of the date of publication and may change without notice. Information is from sources believed reliable, but Nexo makes no warranty as to its accuracy and accepts no liability for any loss arising from reliance on this material.