Markets Today - October 23, 2026
Oct 23•5 min read
Daily analysis of crypto markets and the forces shaping them, from the Nexo research desk.
Bitcoin steadies near $81,700 after a tech-led selloff, with a Fed hold nearly fully priced ahead of next week’s FOMC
Bitcoin steadies near $81,700 on Friday after Thursday’s slide of about 3%, tracking a tech-led selloff in which the Nasdaq Composite lost 2.6%, its worst session since June, over doubts about how the AI buildout will be paid for. U.S. futures are mixed to lower, with the Dow down 0.6%, the S&P 500 down 0.2% and the Nasdaq-100 flat, and the Nasdaq is set for a weekly loss while the S&P 500 and Dow are ahead for the week on defensive buying. Treasuries gained, with the 10-year yield near 4.95%, yet the dollar index at 101.86 stayed close to a three-week low, so the dollar did not provide its usual shelter, while the yen is heading for its best week in over a month and the euro is weighed down by France. Brent is near $114, a five-month high. Next week brings the Fed’s October 27 to 28 meeting, with a hold priced at 91.7% per CME FedWatch, followed by the ECB and the Bank of Japan, so the focus is on what the Fed signals for December. The total crypto market cap sits around $2.7 trillion.
Bitcoin
Bitcoin dipped below $82,000 on Thursday night as about $440 million of leveraged positions, mostly longs, were reset over 24 hours, and it has since steadied, up about 0.5% since midnight UTC. Crypto has been moving with technology shares, so its direction is tied to AI funding news and oil prices. The signals to watch are whether the $80,000 area holds, whether ETF buying continues and whether equity or oil volatility deepens the pullback.
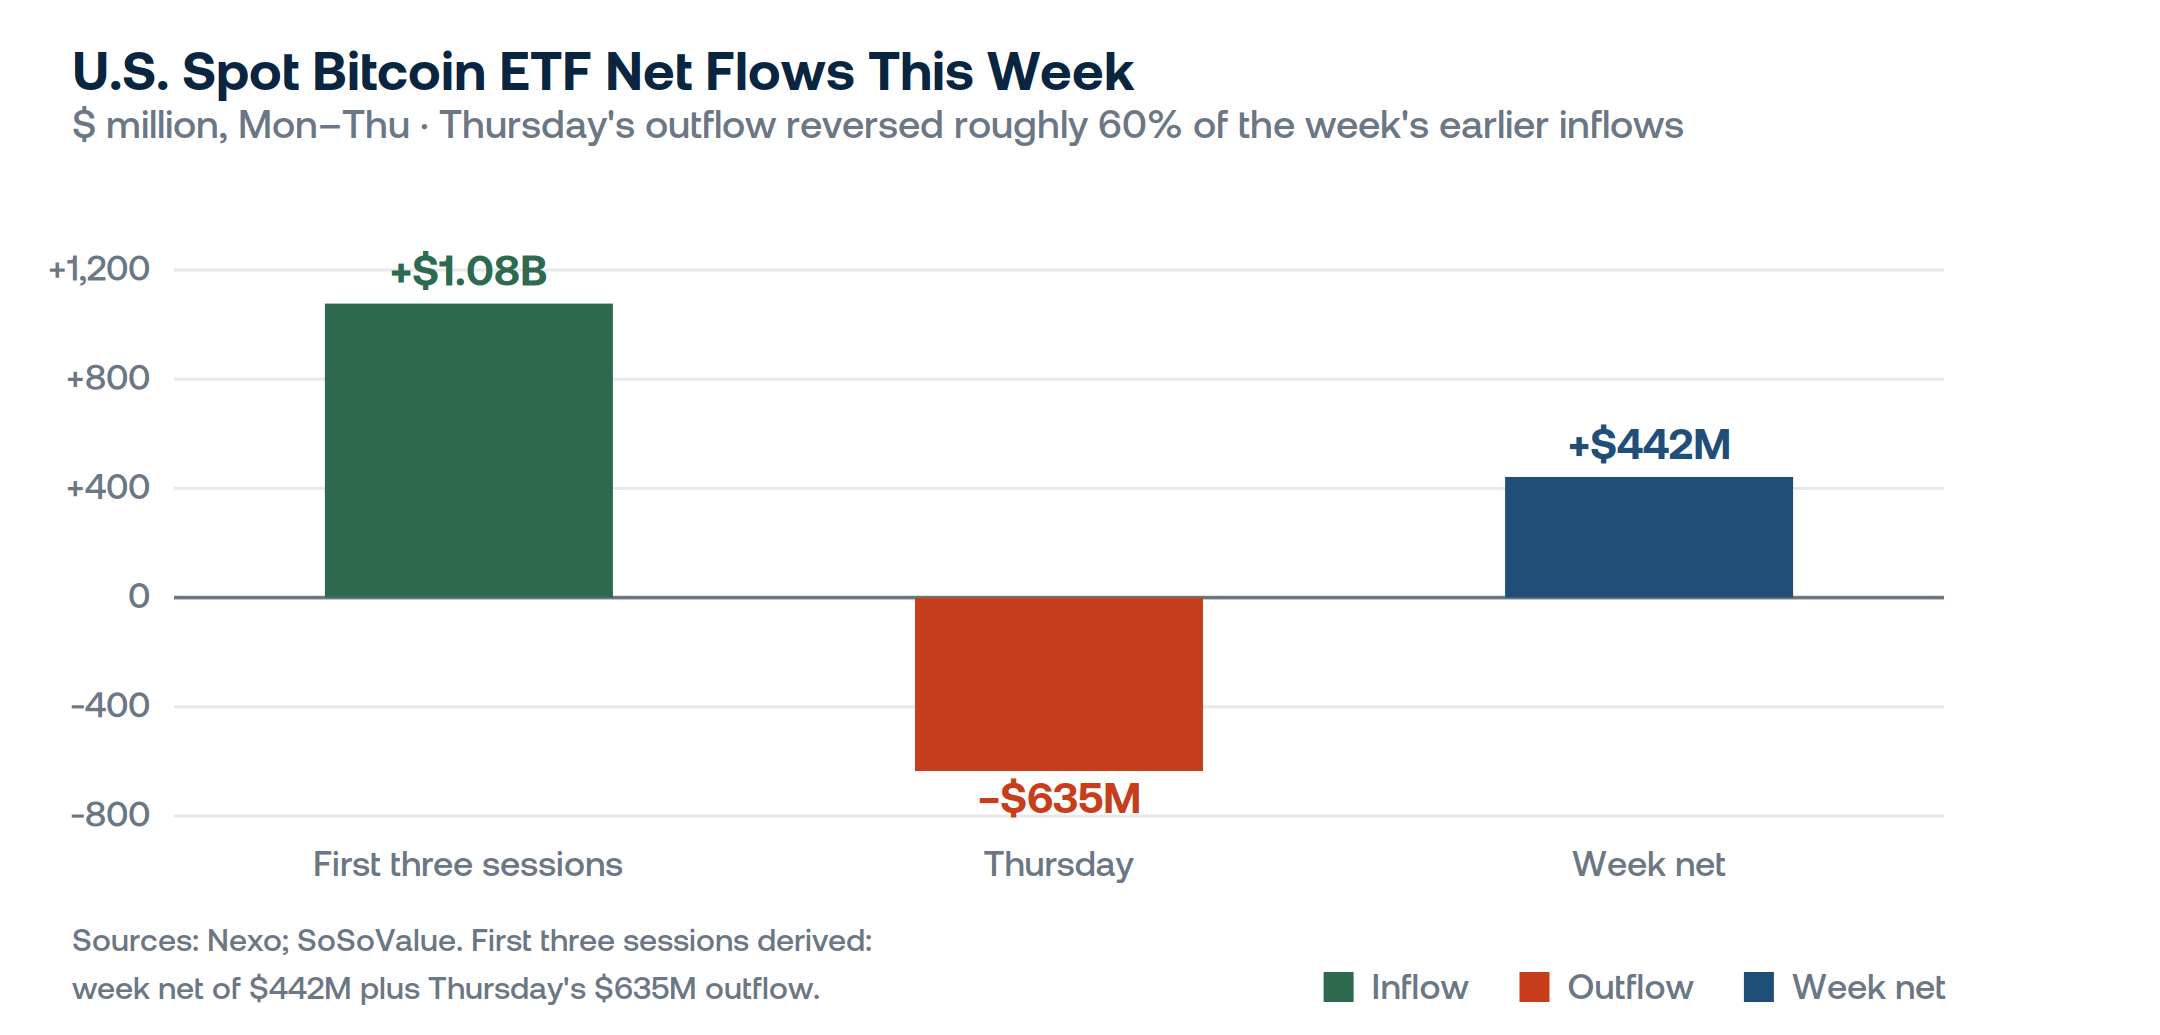
ETF buying has been tactical, not steady, with flows alternating between inflows and outflows from day to day this week. U.S. spot funds took in more than $1 billion over the first three sessions, then lost $635 million on Thursday as Bitcoin fell, per SoSoValue, leaving the week’s net inflow at $442 million.
Derivatives show positioning rebuilding cautiously after the reset. Open interest rose about 1% in both Bitcoin and Ether while prices were flat, liquidations in Bitcoin fell by about two-thirds, and Bitcoin funding edged up to 0.0067% from 0.0041%. Order flow has returned to near neutral after Thursday’s selling. In options, demand for downside protection has cooled in Bitcoin, with the one-week skew near 4% against a mid-month peak around 14%, but it has built in Ether, where it is near 13% and rising.12
Ethereum & Altcoins
Ether trades near $2,390, XRP near $1.32 and Solana near $104, with open interest in XRP and Solana falling faster than their prices, a sign that leveraged longs are being closed. Ether options lean defensive, with puts occupying the top two spots by volume, led by the October 26 $2,200 put, though the data does not show who is buying. Developers postponed Monday’s Glamsterdam rehearsal on the Hoodi test network to study a gas-accounting change that could alter how existing contracts react to failed transactions, and no new date is set. The mechanism has been shown in theory, but no major live protocol has been found to be exploitable, and the upgrade’s earlier test on Sepolia finished on October 6.
Macro & Institutional
The selloff is about funding, not demand. Meta fell about 7% on Thursday after announcing new non-voting shares as its cash flow turned negative for the first time in over ten years, and the semiconductor index fell 6.7% after Nvidia’s chief executive warned that the money sought for AI projects outstrips what is on offer. With sentiment now so negative, a near-term bounce is possible, but funding is likely to stay tighter than before. Earnings are holding up, with S&P 500 third-quarter profit growth now forecast at 32.3%, up from 30.7%. Telecom shares are down more than 3% premarket on a report that SpaceX is exploring a wireless carrier program, and the STOXX 600 is down 0.6% near a two-week low, with chip names down 2% to 6%.
Currencies show a shift in where investors shelter. Traders trimmed hike expectations as tech sold off, pulling the 10-year yield down almost 20 basis points on Thursday to near 4.95%, its biggest daily drop since March 2023, but the dollar gained little from the flight to safety. The yen led, with the dollar touching 156.06, its lowest in over a month, supported by Japanese core inflation rising to 2.1% in September, above the Bank of Japan’s 2% target for the first time in nine months. The euro is near $1.12 and set for a weekly loss, and it slid to its lowest against the yen since October 2025, as the extra yield investors demand for holding French debt reached its highest since the 2011 euro-zone crisis and French business activity unexpectedly shrank in October, with nationwide protests planned for Saturday.
Brent trades near $114 as Middle East tensions around Saudi energy infrastructure keep supply risks high and feed inflation worries before the Fed meets. A December Fed hike is still the base case, priced at about 75% by CME FedWatch, though well below the near-full pricing seen earlier.
Looking Ahead
Today brings the U.S. flash PMIs, a read on growth that could shape rate expectations, and the final University of Michigan consumer survey for October. Next week is the key one for rates, with the Fed meeting and core PCE together framing the December decision. The Fed decides on Wednesday, October 28, with a hold nearly fully priced, so its guidance matters more than the decision itself. Core PCE follows on Thursday, October 29, the day after the decision, and as the Fed’s preferred inflation gauge it is the first hard inflation reading after the meeting and the test for the December hike markets still expect. The ECB also decides on Thursday and the Bank of Japan on Friday, October 30, and payrolls follow on November 6. For Bitcoin, the test is whether ETF flows turn consistent and whether the $80,000 area holds.
Author: Iliya Kalchev, Analyst at Nexo’s Dispatch
This material is produced by Nexo for informational purposes only and does not constitute financial, investment, legal, or tax advice, or a recommendation to transact in any digital asset. Views are the author's as of the date of publication and may change without notice. Information is from sources believed reliable, but Nexo makes no warranty as to its accuracy and accepts no liability for any loss arising from reliance on this material.